U.S. Listed Dental DSO 2026Q1: Net Profit Turns to Loss, Equity Incentives Cause Significant Increase in Service Costs U.S. listed Dental Service Organization (DSO) reported its 2026Q1 finan…Issuing time:2026-05-14 13:00
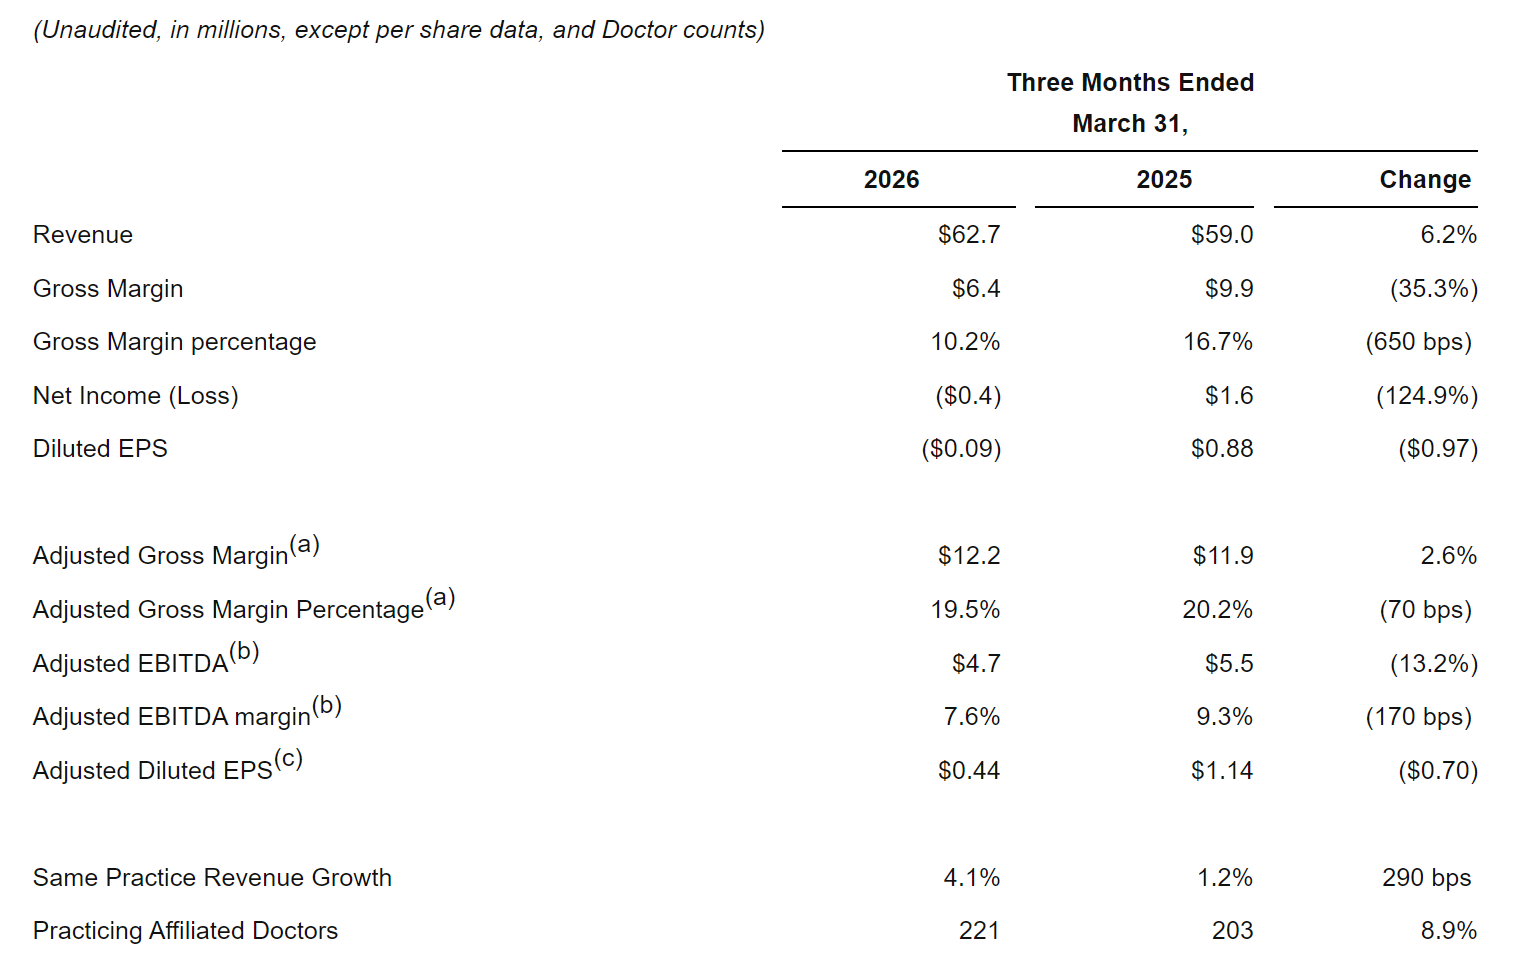
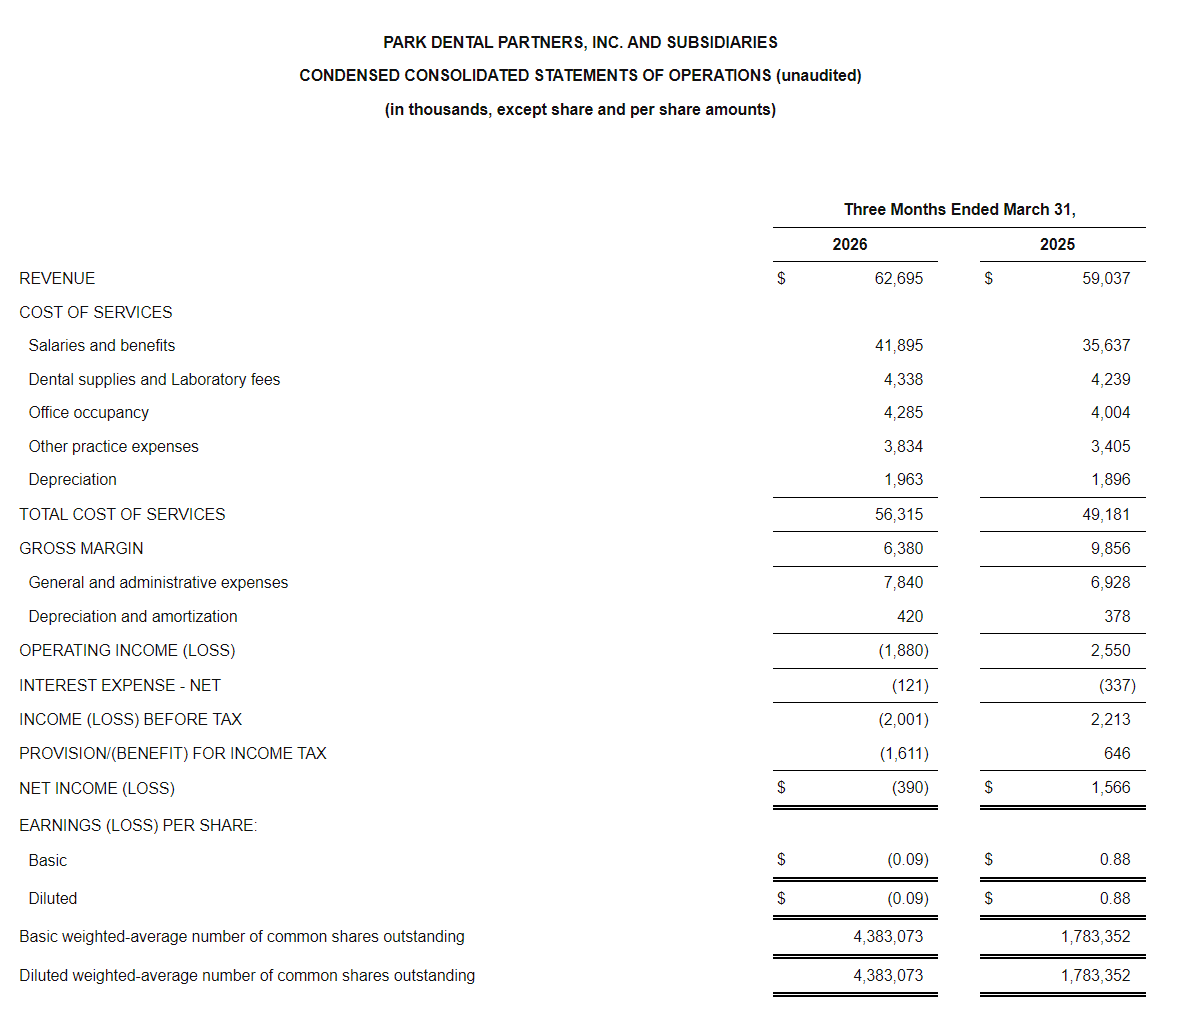
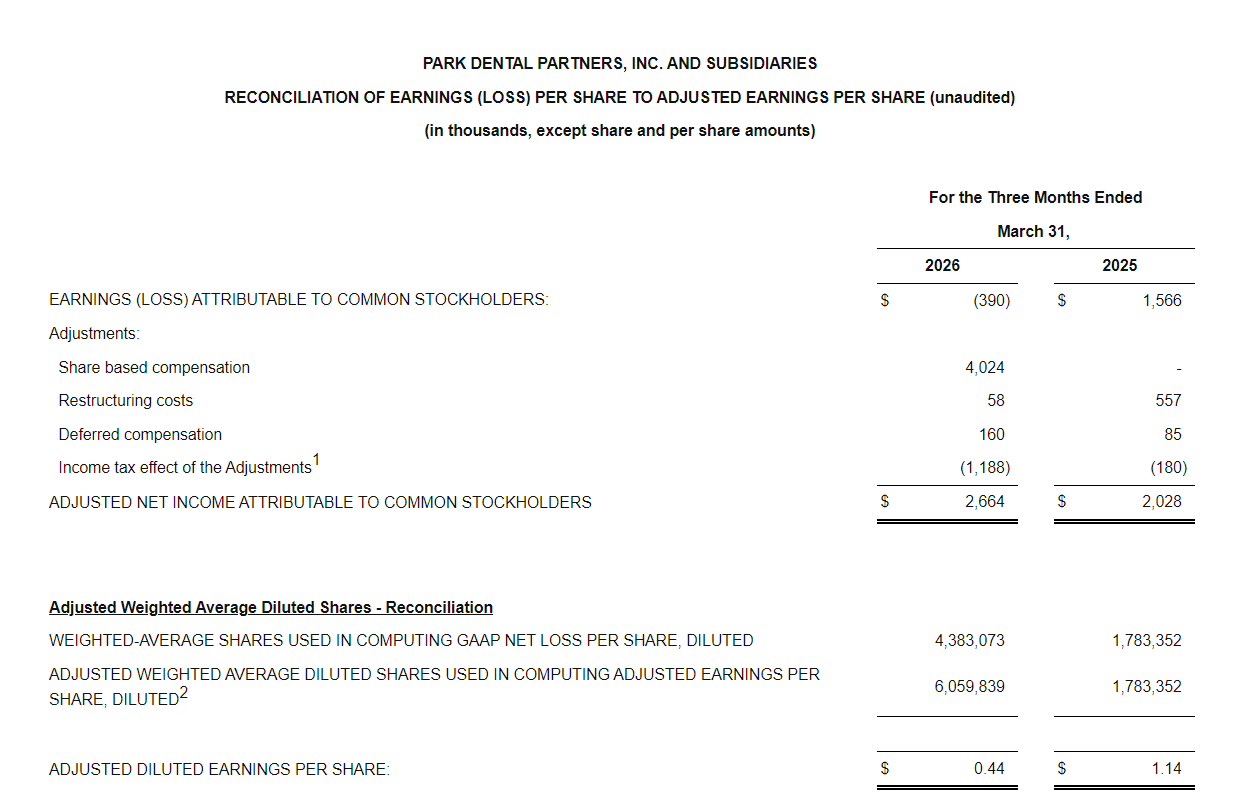
DentalGoodNews|U.S. Oral DSO listed company Park Dental Partners, Inc. (NASDAQ: PARK) released its unaudited financial report for the first quarter of 2026 (ended March 31) on May 13, 2026. According to the financial data, the company's first-quarter revenue was $62.695 million (approximately RMB 426 million), a year-over-year increase of 6.22%. Net income/loss turned from profit to a loss of $0.39 million (approximately RMB 2.648 million), a year-over-year decrease of 124.90% (net income of $1.566 million, approximately RMB 10.633 million, in the same period last year). The first quarter recognized share-based compensation expenses totaling $4.024 million (approximately RMB 27.323 million) for the first time. The company stated this was the primary factor driving net profit from positive to negative, fully offsetting the profit space generated by revenue growth in the same period. In terms of business structure, General Practice revenue was $46.1 million (approximately RMB 313 million), a year-over-year increase of 6.4%, accounting for approximately 73.5% of total revenue; Multi-Specialty Practice revenue was $16.6 million (approximately RMB 113 million), a year-over-year increase of 5.7%. Both business lines achieved positive growth, with the proportion of general practice revenue remaining roughly flat compared to the previous year.
Cost of services totaled $56.315 million (approximately RMB 382 million), an increase of $7.134 million (approximately RMB 48.44 million) year-over-year, a growth rate of 14.51%. Among this, dental consumables and laboratory fees were $4.338 million (approximately RMB 29.455 million), an increase of $0.099 million (approximately RMB 0.672 million) year-over-year; other clinic operating expenses were $3.834 million (approximately RMB 26.033 million), an increase of $0.429 million (approximately RMB 2.913 million) year-over-year. Gross margin was $6.38 million (approximately RMB 43.32 million), a year-over-year decrease of 35.27%; gross margin rate was 10.2%, a decrease of 650 basis points year-over-year (16.7% in the same period last year). Adjusted Gross Margin was $12.205 million (approximately RMB 82.872 million), an increase of $0.305 million (approximately RMB 2.071 million) year-over-year; adjusted gross margin rate was 19.5%, narrowing by 70 basis points year-over-year (20.2% in the same period last year). General and Administrative (G&A) expenses were $7.84 million (approximately RMB 53.234 million), an increase of $0.912 million (approximately RMB 6.192 million) year-over-year, primarily driven by share-based compensation, acquisition-related costs, and public company operating costs post-IPO, partially offset by a reduction in IPO preparation expenses from 2025. The first-quarter operating loss was $1.88 million (approximately RMB 12.765 million), compared to an operating profit of $2.55 million (approximately RMB 17.315 million) in the same period last year.
Pre-tax loss was $2.001 million (approximately RMB 13.587 million); benefit for income tax was $1.611 million (approximately RMB 10.945 million), mainly from tax benefits related to share-based compensation; the final net loss was $0.39 million (approximately RMB 2.648 million). On an adjusted basis, adjusted diluted EPS was $0.44 (approximately RMB 2.99; $1.14, approximately RMB 7.74, in the same period last year), with the decline primarily due to the expansion of outstanding shares post-IPO—weighted average adjusted diluted shares increased from 1.783 million to 6.0598 million. Adjusted EBITDA was $4.745 million (approximately RMB 32.219 million), a year-over-year decrease of 13.17% ($5.465 million, approximately RMB 37.107 million, in the same period last year); adjusted EBITDA margin was 7.6%, narrowing by 170 basis points year-over-year (9.3% in the same period last year). In the first quarter, the company completed one general practice acquisition (Tucson, Arizona, announced on January 23, 2026). The acquisition contributed approximately $0.8 million (approximately RMB 5.432 million) in quarterly revenue, and the company stated its impact on net profit was not material.
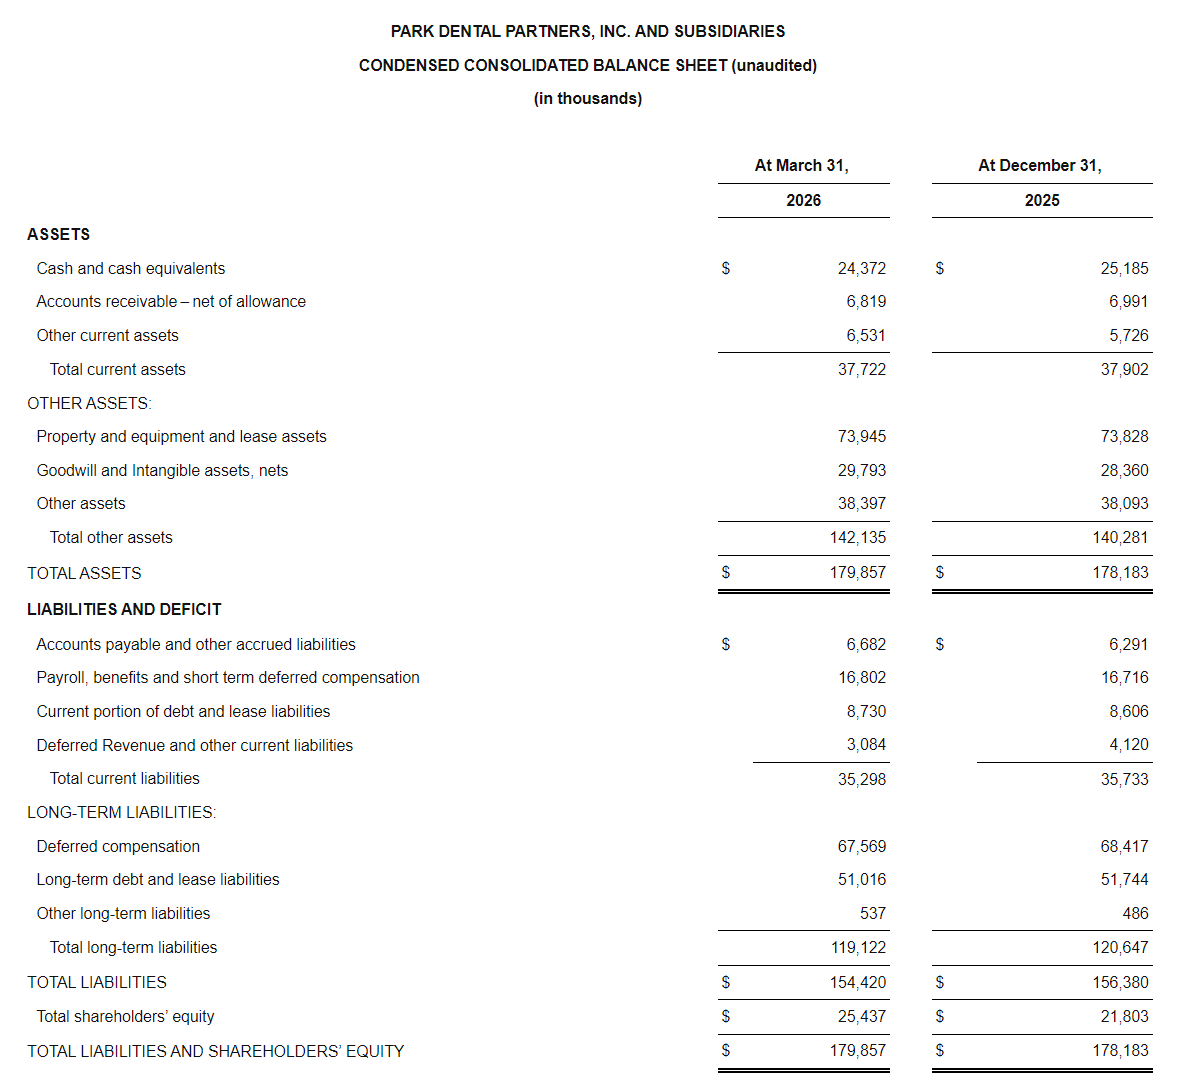
On the balance sheet side, as of March 31, 2026, cash and cash equivalents were $24.372 million (approximately RMB 165 million; $25.185 million, approximately RMB 171 million, at the beginning of the year); interest-bearing debt was approximately $11.5 million (approximately RMB 78.085 million); the $15 million (approximately RMB 102 million) line of credit was undrawn at quarter-end; total assets were $179.857 million (approximately RMB 1.221 billion), and shareholders' equity was $25.437 million (approximately RMB 173 million). Goodwill and intangible assets, net, were $29.793 million (approximately RMB 202 million), accounting for 16.6% of total assets and 117.1% of shareholders' equity.
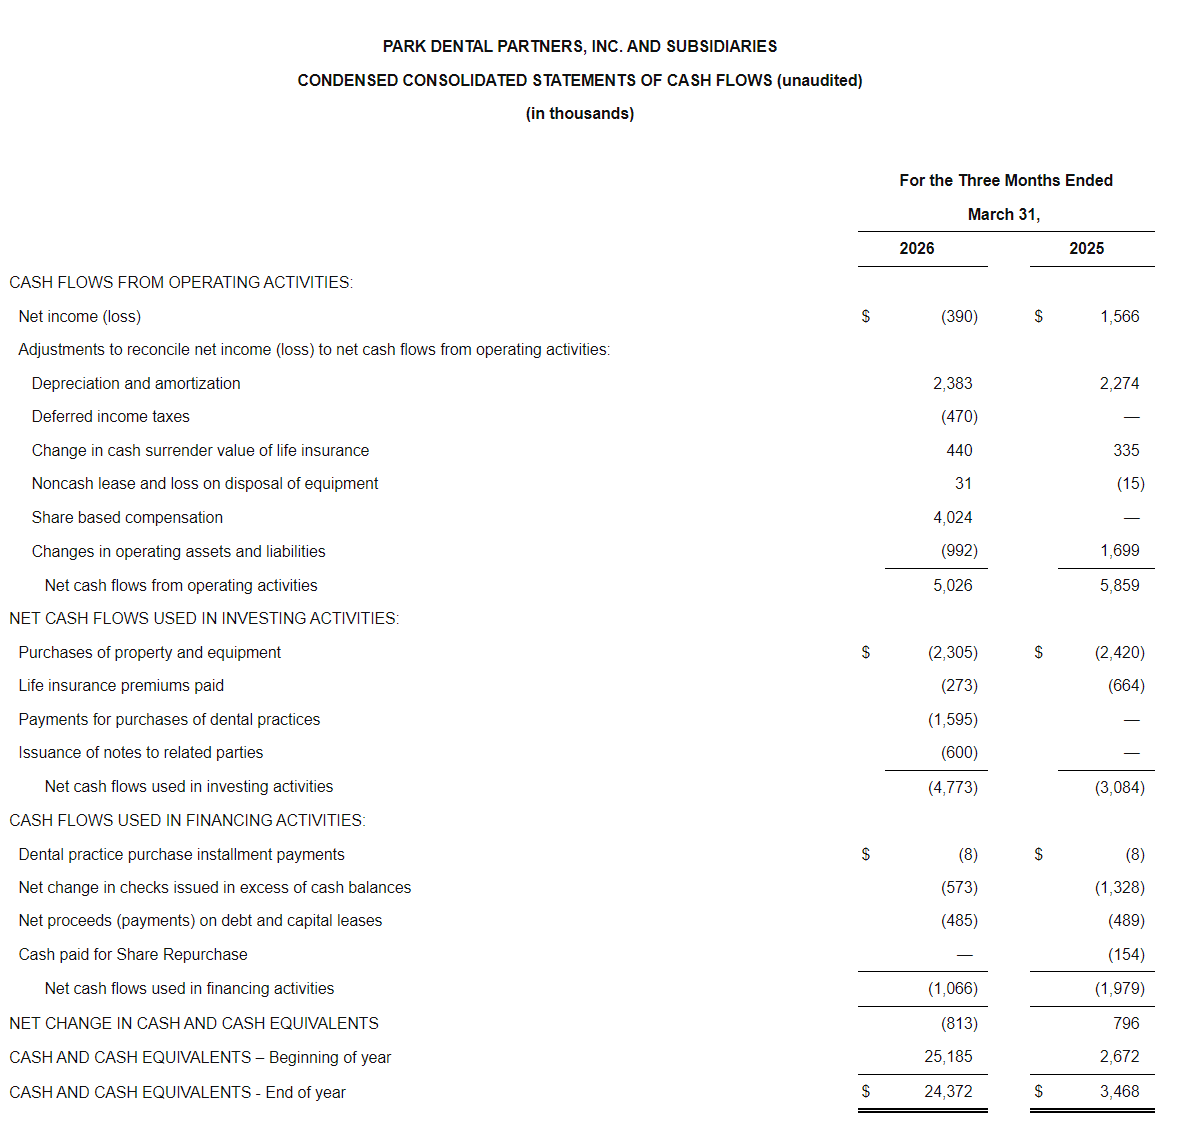
In terms of cash flow, operating cash flow in the first quarter was $5.026 million (approximately RMB 34.127 million), a decrease of $0.833 million (approximately RMB 5.656 million, -14.21%, compared to $5.859 million, approximately RMB 39.783 million, in the same period last year), mainly dragged down by changes in operating assets and liabilities of -$0.992 million (approximately RMB 6.736 million). The book net loss was adjusted through non-cash items such as share-based compensation ($4.024 million, approximately RMB 27.323 million) and depreciation and amortization ($2.383 million, approximately RMB 16.181 million), with overall operating cash recovery capacity maintained. Capital expenditures were $2.305 million (approximately RMB 15.651 million); expenditures for dental practice acquisitions were $1.595 million (approximately RMB 10.83 million); net cash outflow from financing activities was $1.066 million (approximately RMB 7.238 million). On the operational metrics front, as of March 31, 2026, the company had 221 affiliated doctors (203 in the same period last year, an increase of 8.87%) and 86 affiliated practices. Patient visits in the first quarter were 178,527 (175,940 in the same period last year); same practice revenue growth was 4.1%, an increase of 290 basis points from 1.2% in the same period last year; the 12-month rolling patient retention rate was 90.1%, an increase of 90 basis points from 89.2% in the same period last year. Both doctor scale expansion and patient retention rate improved simultaneously, supporting clinic capacity.
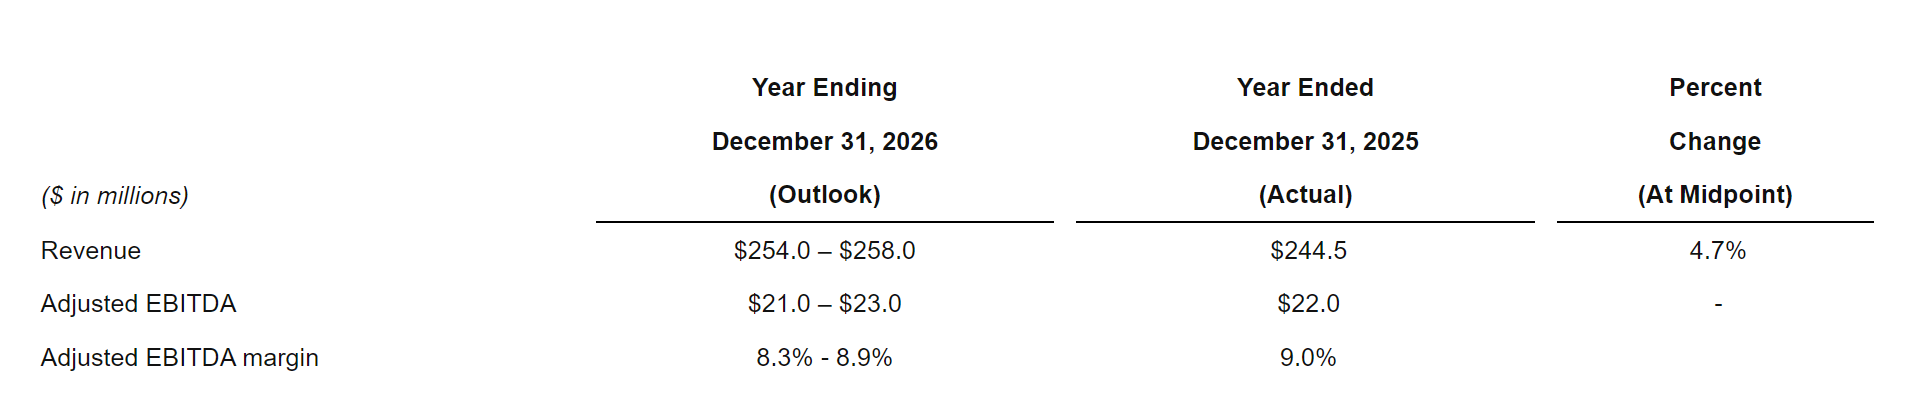
For 2026, the company maintains its full-year guidance unchanged: expected same practice revenue growth of 3.5%–5.0%, and full-year public company costs of approximately $2 million (approximately RMB 13.58 million). It should be noted that the guidance does not include the impact of future acquisitions or new practice openings that have not yet been completed.
Article classification:
Industry Finance
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|