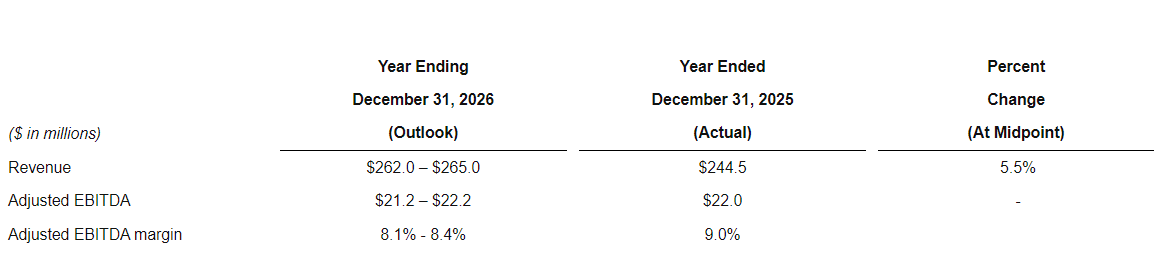U.S. Dental DSO Public Company 2026Q3: Revenue $64.9 Million, Up 6% YoY; Gross Profit Down 13.3% YoYIssuing time:2026-11-13 13:44
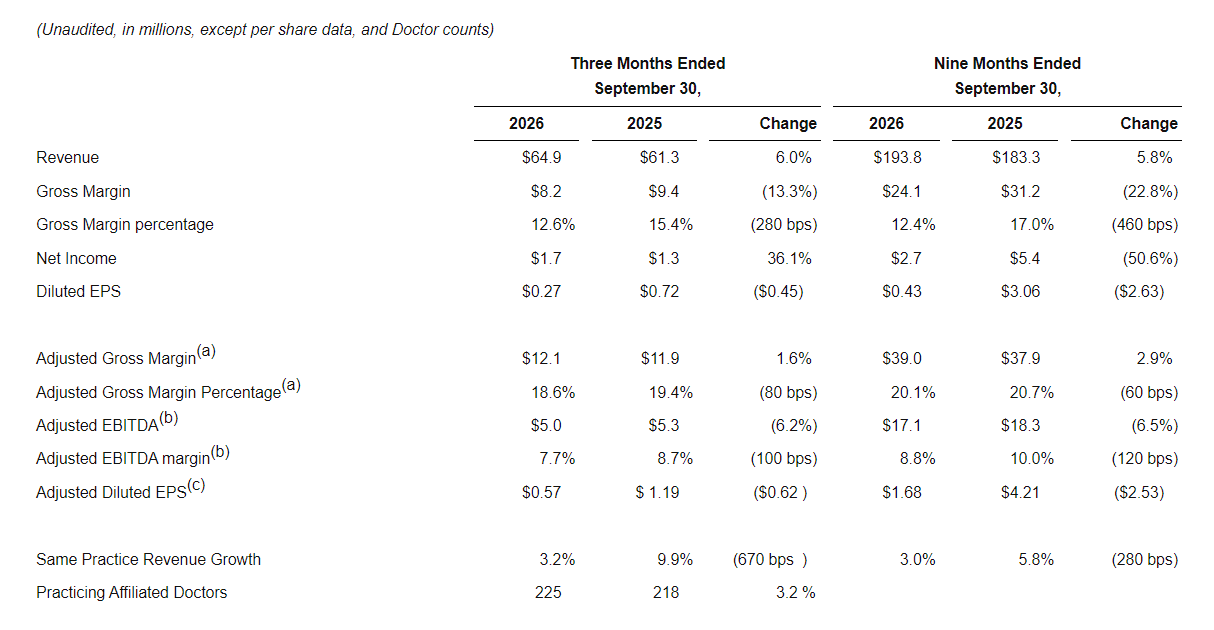
Operating revenue of $64.9 million (approximately RMB 436 million) / Gross margin down 13.3% year-over-year / Patient retention rate up 0.4 percentage points year-over-year DentalGoodNews|On November 12, 2026, U.S.-listed dental service support company Park Dental Partners, Inc. (NASDAQ: PARK) reported unaudited results for the third quarter of 2026: operating revenue of $64.9 million (approximately RMB 436 million), up 6.0% year-over-year; gross profit of approximately $8.2 million (approximately RMB 55 million), down 13.3% year-over-year, with gross margin declining to 12.6% from 15.4% in the prior-year period. The company said revenue growth was primarily driven by changes in fee and reimbursement levels, clinic acquisitions, and increased clinical hours. Clinics acquired over the past 12 months contributed approximately $1.2 million (approximately RMB 8.06 million) in revenue during the quarter. Same-clinic revenue grew 3.2% year-over-year, down from 9.9% in the prior-year period, a deceleration of 6.7 percentage points. The company defines same-clinic as clinics that have been operating for at least 13 full months as of the end of the reporting period and were not closed or sold during that period.
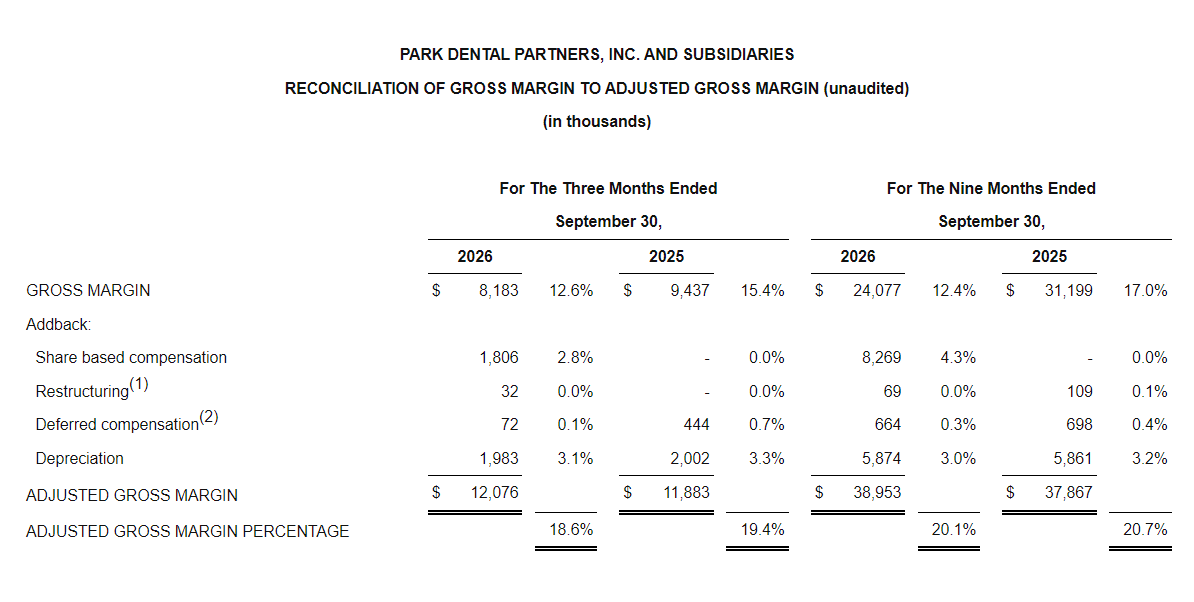
On profitability, gross margin declined 2.8 percentage points year-over-year in the third quarter. The company cited increased salary and benefit expenses, including physician equity compensation related to its transition to a public company, as weighing on gross margin performance. Excluding equity compensation, depreciation and other items, adjusted gross profit was approximately $12.1 million (approximately RMB 81.3 million), up 1.6% year-over-year; adjusted gross margin was 18.6%, down 0.8 percentage points year-over-year. Third-quarter net income was approximately $1.7 million (approximately RMB 11.4 million), compared with approximately $1.3 million (approximately RMB 8.73 million) in the prior-year period. However, the financial statements showed an operating loss of $114,000 (approximately RMB 766,000) and a pre-tax loss of $203,000 (approximately RMB 1.364 million) for the quarter, while recognizing an income tax benefit of $1.905 million (approximately RMB 12.8 million). Adjusted EBITDA was approximately $5.0 million (approximately RMB 33.6 million), down 6.2% year-over-year, with the Adjusted EBITDA margin declining to 7.7% from 8.7%.
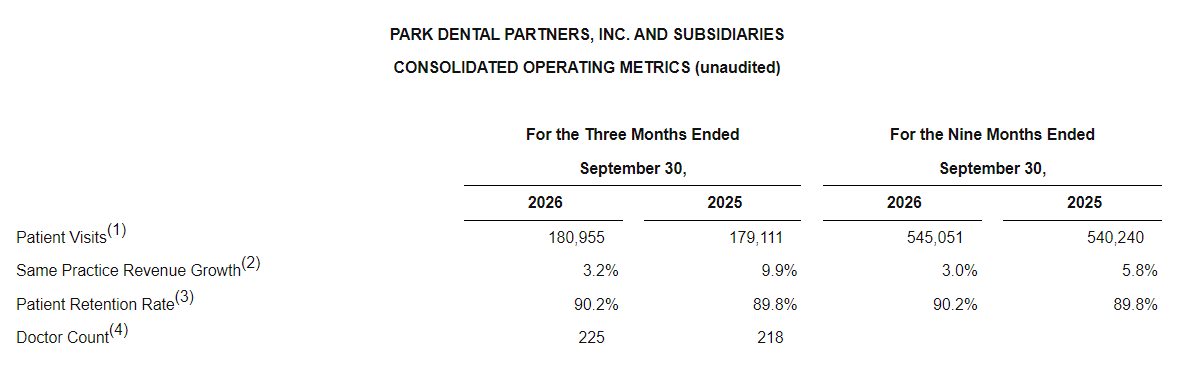
As of September 30, 2026, Park Dental Partners supported a total of 88 affiliated clinics and 225 affiliated doctors, up from 218 in the prior-year period. In the third quarter, affiliated general dental clinics recorded 180,955 patient visits, compared with 179,111 in the prior-year period, an increase of approximately 1.0% year-over-year; the patient retention rate was 90.2%, up 0.4 percentage points from 89.8% in the prior-year period. On business expansion, the company completed the acquisition of Village Family Dental DSO on November 6, adding 12 clinic locations and 47 doctors in North Carolina, expanding its footprint from 3 states to 4 states. The transaction closed after the end of the third quarter and therefore was not included in quarterly results; its financial performance will be consolidated into the company's financial statements starting in the fourth quarter.
For full-year outlook, the company expects 2026 revenue of $262 million to $265 million (approximately RMB 1.760 billion to 1.780 billion) and Adjusted EBITDA of $21.2 million to $22.2 million (approximately RMB 142 million to 149 million). The outlook incorporates the expected contribution from the closing of Village Family DSO and takes into account increased investment in clinical personnel in the second half and the impact of a cybersecurity incident in the third quarter.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|