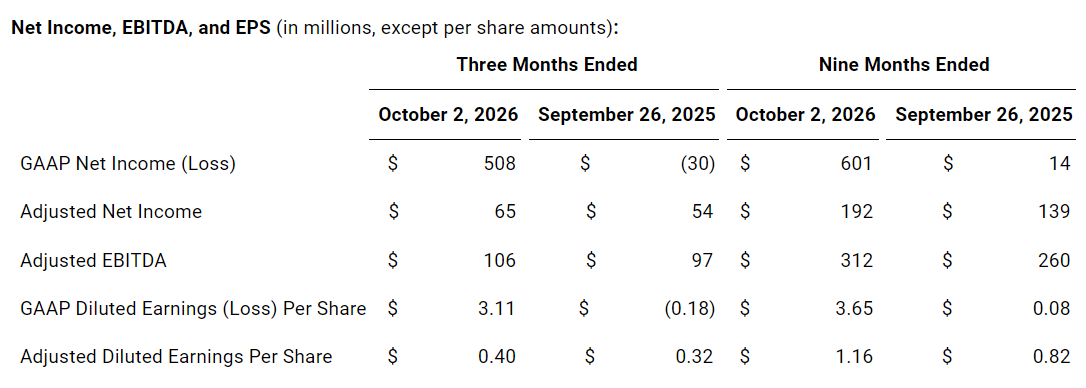Envista 2026Q3: Revenue of $692 million, up 3.22% year-over-year, with implants achieving mid-single-digit growthIssuing time:2026-11-06 19:22
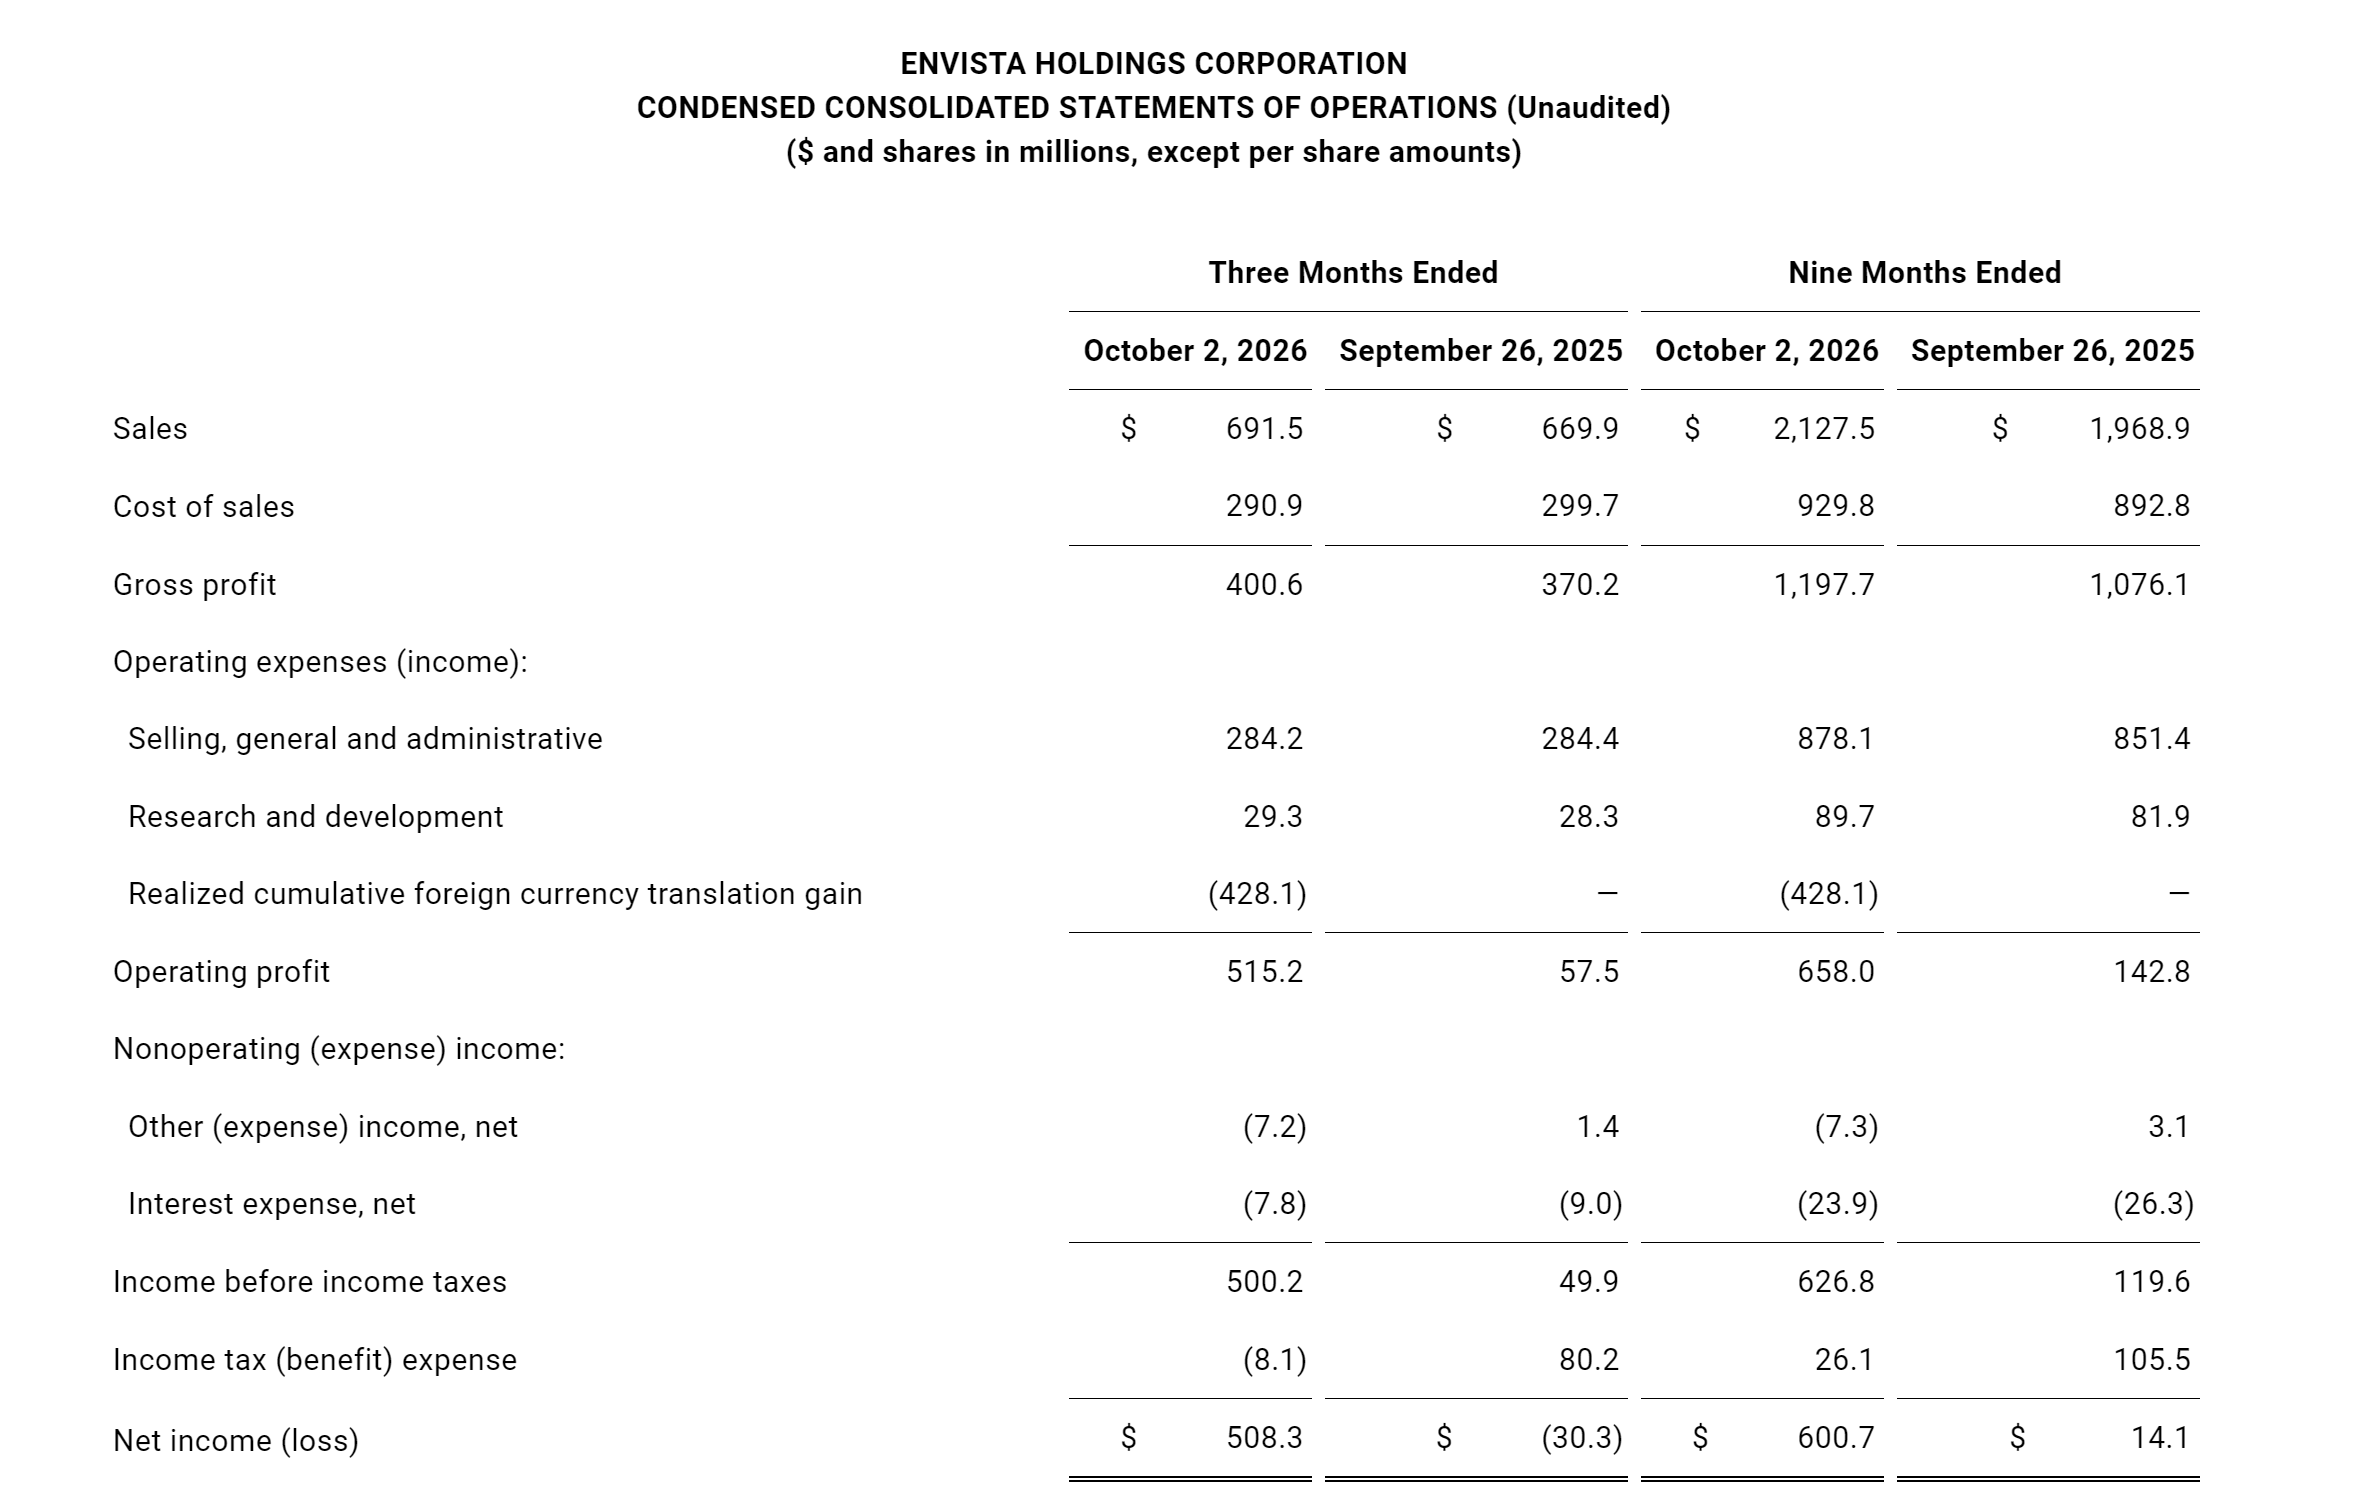
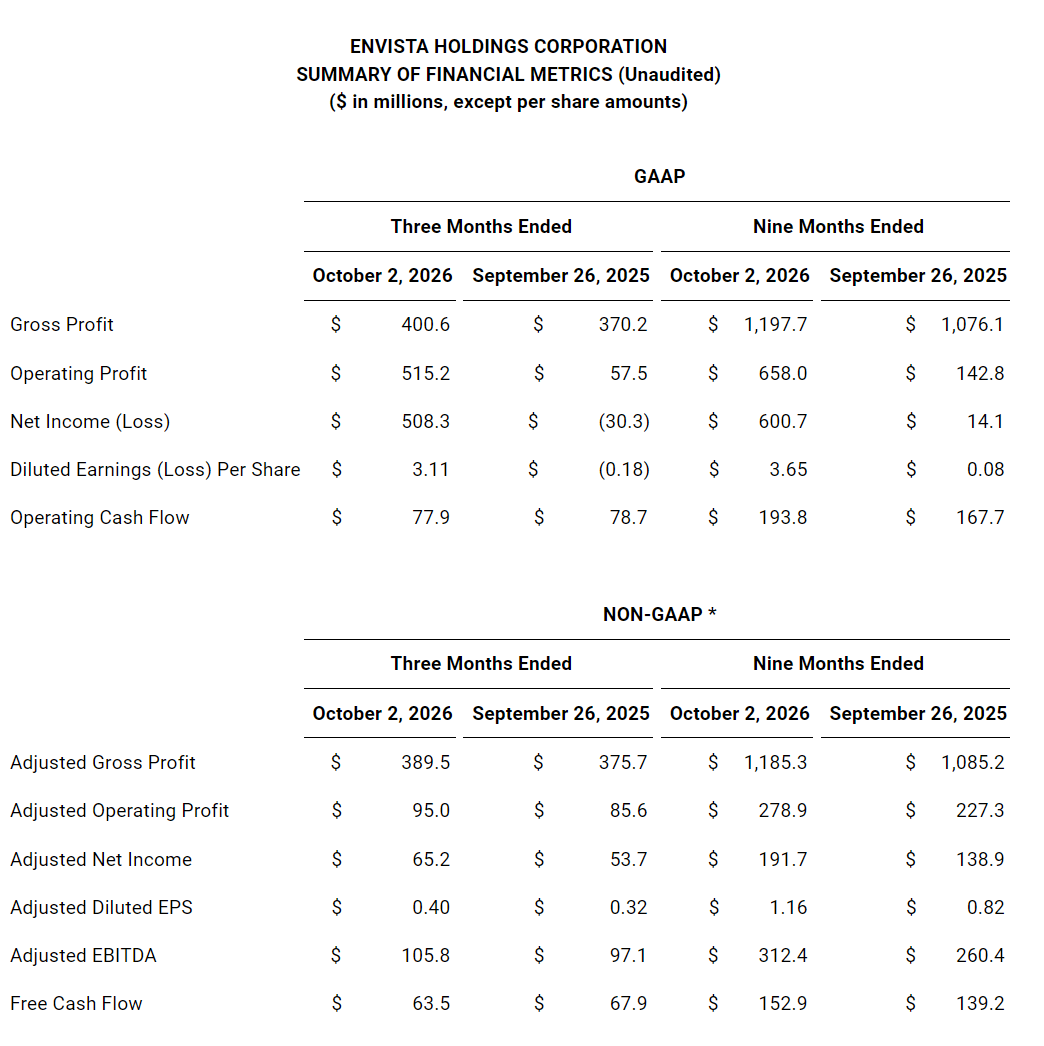
Q3 revenue $691.5 million / Q3 net income $508.3 million / Equipment & Consumables segment Q3 revenue up 3.94% year-over-year DentalGoodNews|On November 4, 2026, Envista Holdings Corporation reported unaudited third-quarter 2026 results. Quarterly revenue was $691.5 million (approximately RMB 4.645 billion), up 3.22% from $669.9 million (approximately RMB 4.500 billion) in the same period of 2025; Core Sales Growth was 2.7%. GAAP net income was $508.3 million (approximately RMB 3.415 billion), compared with a net loss of $30.3 million (approximately RMB 204 million) in the prior-year period. For the first three quarters of 2026, cumulative revenue was $2,127.5 million (approximately RMB 14.293 billion), up 8.06% year-over-year; cumulative GAAP net income was $600.7 million (approximately RMB 4.036 billion), compared with $14.1 million (approximately RMB 95 million) in the same period of 2025. The statistical cutoff date for both quarterly and cumulative data was October 2, 2026. Management said on the earnings call that the global dental market in the third quarter showed no material change compared with the first half of the year. By business category, insurance-covered procedures such as prevention, diagnostics and restorative continued to perform relatively steadily, while elective treatments such as Orthodontics and implants remained below their prior high historical levels. In addition, in the China market, the company's third-quarter business declined by a low double-digit percentage year-over-year, mainly due to proactive destocking in the Orthodontics channel in response to Volume-Based Procurement (VBP). Management had previously expected the VBP-related impact in the third quarter to be broadly in line with expectations; considering the offset from implant business growth in the same period, China operations still had a certain net drag on the company's overall revenue in the quarter, but no significant VBP-related impact is expected in the fourth quarter.
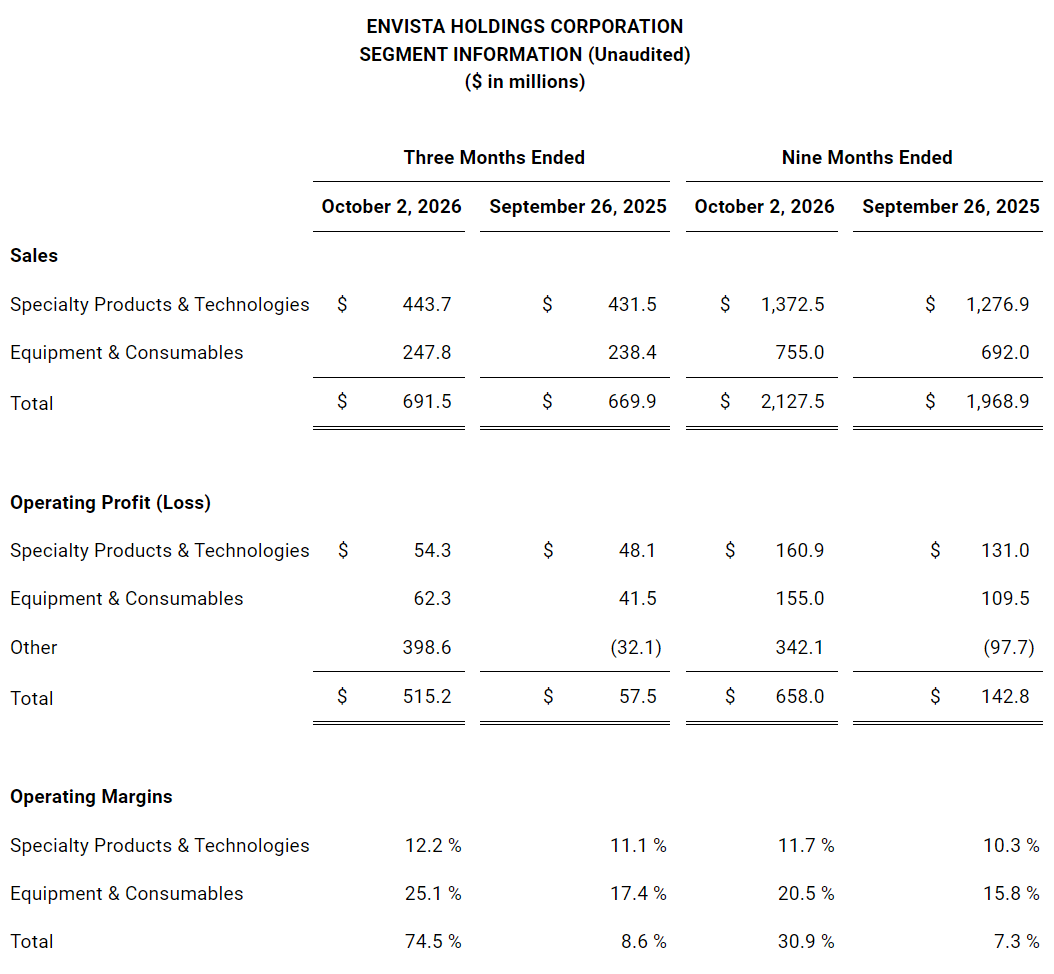
By segment, Specialty Products & Technologies third-quarter revenue was $443.7 million (approximately RMB 2.981 billion), compared with $431.5 million (approximately RMB 2.899 billion) in the same period of 2025, up 2.83% year-over-year; Core Sales Growth was 2.0%. Equipment & Consumables third-quarter revenue was $247.8 million (approximately RMB 1.665 billion), compared with $238.4 million (approximately RMB 1.602 billion) in the prior-year period, up 3.94% year-over-year; Core Sales Growth was 4.1%. By specific business line, management said on the call that the brackets and archwires business declined by a high single-digit percentage due to VBP-related channel destocking in China. The implant business achieved mid single-digit growth, with positive growth maintained in all major regions; new product launches, the regenerative Biomaterial business and the Versah acquisition all contributed to growth. Within Equipment & Consumables, the Consumables business achieved low single-digit growth, affected by a higher prior-year base; the diagnostics business achieved mid single-digit growth, with contributions from hardware, software and services. In addition, the company opened the Spark European Design Center in Madrid, Spain, in an earlier quarter, complementing its existing facilities in North America and Asia. On profitability, third-quarter GAAP Operating Profit was $515.2 million (approximately RMB 3.461 billion), compared with $57.5 million (approximately RMB 386 million) in the same period of 2025. Adjusted operating profit was $95.0 million (approximately RMB 638 million), compared with $85.6 million (approximately RMB 575 million) in the prior-year period; Adjusted Operating Margin rose to 13.7% from 12.8%. Third-quarter Adjusted EBITDA was $105.8 million (approximately RMB 711 million), compared with $97.1 million (approximately RMB 652 million) in the prior-year period, up 8.96% year-over-year; Adjusted EBITDA margin was 15.3%, up 80 basis points from the prior-year period. Specialty Products & Technologies' adjusted operating margin decreased to 15.0% from 15.5% in the third quarter of 2025; Equipment & Consumables rose to 22.4% from 20.1%.
Third-quarter Adjusted Net Income was $65.2 million (approximately RMB 438 million), compared with $53.7 million (approximately RMB 361 million) in the same period of 2025, up 21.42% year-over-year. The difference between GAAP net income and adjusted net income mainly came from a $428.1 million foreign currency translation gain, which arose from the liquidation of international legal entities, is a non-cash item, and is excluded from adjusted net income and Adjusted EPS. On earnings per share, third-quarter GAAP Diluted EPS (Earnings Per Share) was $3.11 (approximately RMB 20.89); Adjusted Diluted EPS was $0.40 (approximately RMB 2.69), up 25% from $0.32 (approximately RMB 2.15) in the same period of 2025.
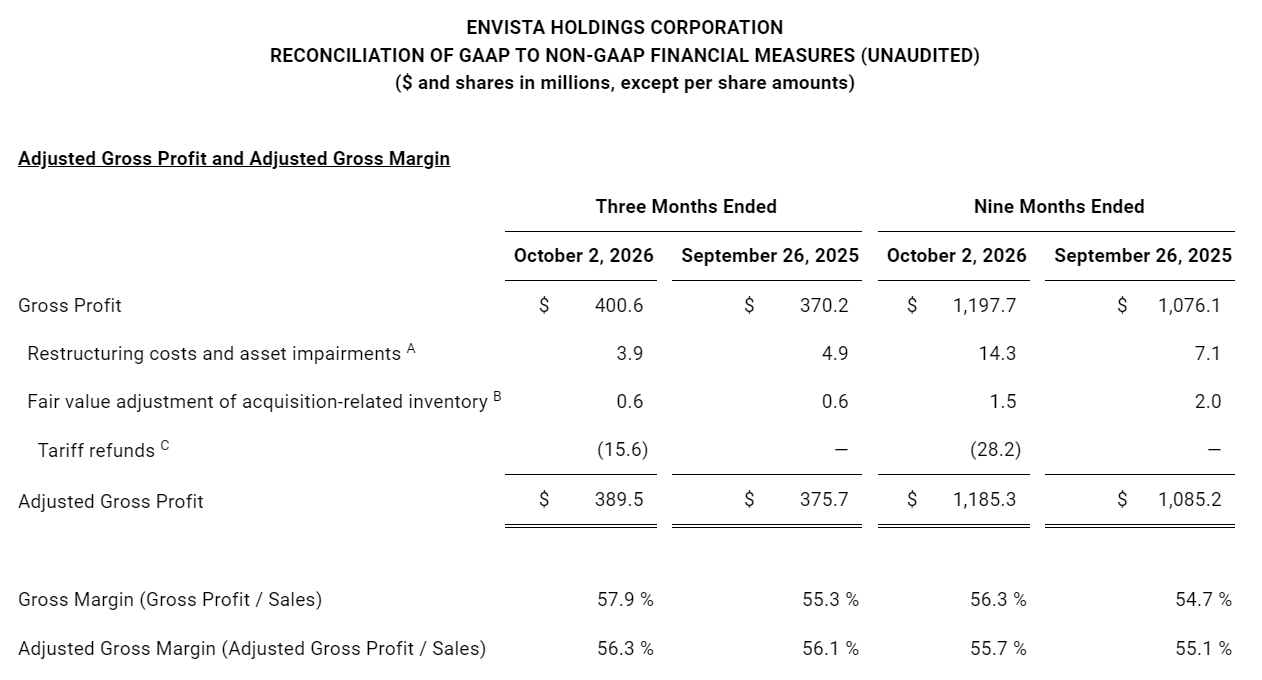
Third-quarter GAAP Gross Margin was 57.9%, compared with 55.3% in the same period of 2025; adjusted gross margin was 56.3%, compared with 56.1% in the prior-year period. The adjusted basis adjusts for items including tariff refunds, restructuring costs, asset impairments and acquisition-related inventory fair value changes. On expenses, third-quarter R&D expense was $29.3 million (approximately RMB 197 million), compared with $28.3 million (approximately RMB 190 million) in the same period of 2025; selling, general and administrative expense was $284.2 million (approximately RMB 1.909 billion), compared with $284.4 million (approximately RMB 1.911 billion) in the prior-year period. The third-quarter effective tax rate decreased by nearly 6 percentage points from the prior-year period, and the company expects a full-year tax rate of approximately 25.5% on adjusted pre-tax income.
On cash flow, third-quarter GAAP Operating Cash Flow was $77.9 million (approximately RMB 523 million); non-GAAP Free Cash Flow was $63.5 million (approximately RMB 427 million). For the first three quarters of 2026, cumulative GAAP Operating Cash Flow was $193.8 million (approximately RMB 1.302 billion); cumulative non-GAAP Free Cash Flow was $152.9 million (approximately RMB 1.027 billion). As of October 2, 2026, the company had cash and cash equivalents of $1,158.8 million (approximately RMB 7.785 billion), compared with $1,211.7 million (approximately RMB 8.140 billion) at the end of 2025; long-term debt was $1,429.0 million (approximately RMB 9.600 billion), compared with $1,448.3 million (approximately RMB 9.730 billion) at the end of 2025. The ratio of net debt to Adjusted EBITDA was approximately 0.6x. The company repurchased approximately 386,000 shares in the third quarter for approximately $10 million (approximately RMB 67 million). As of the end of the quarter, approximately $273 million (approximately RMB 1.834 billion) remained under the Share repurchase program.
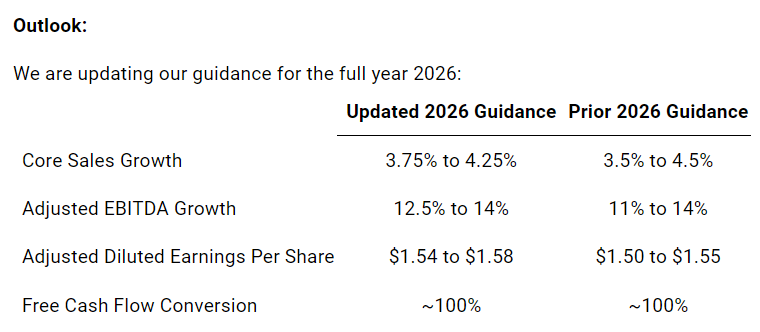
The company updated its full-year 2026 guidance: Core Sales Growth is now expected at 3.75%–4.25%, compared with the previous 3.5%–4.5%; Adjusted EBITDA growth is now expected at 12.5%–14%, compared with the previous 11%–14%. Adjusted Diluted EPS is now expected at $1.54–$1.58 (approximately RMB 10.35–10.61), compared with the previous $1.50–$1.55 (approximately RMB 10.08–10.41), and the Free Cash Flow conversion guidance remains at approximately 100%.
Article classification:
Industry Finance
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|