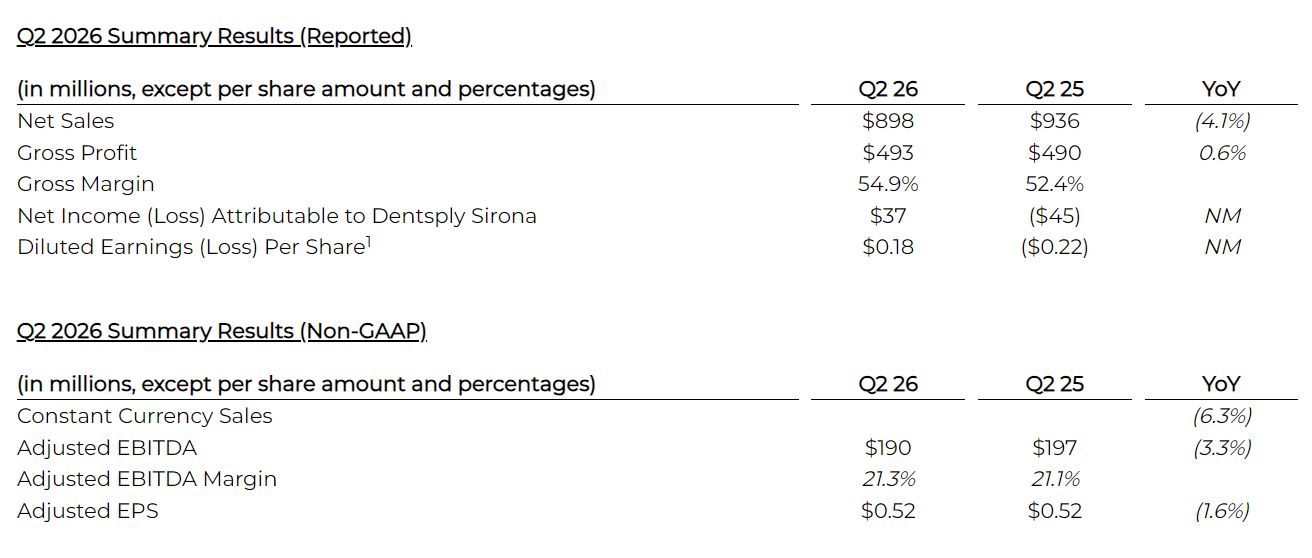Dentsply Sirona 2026 Q2: Revenue of $898 Million, Gross Margin Improved to 54.9%Issuing time:2026-08-07 19:35
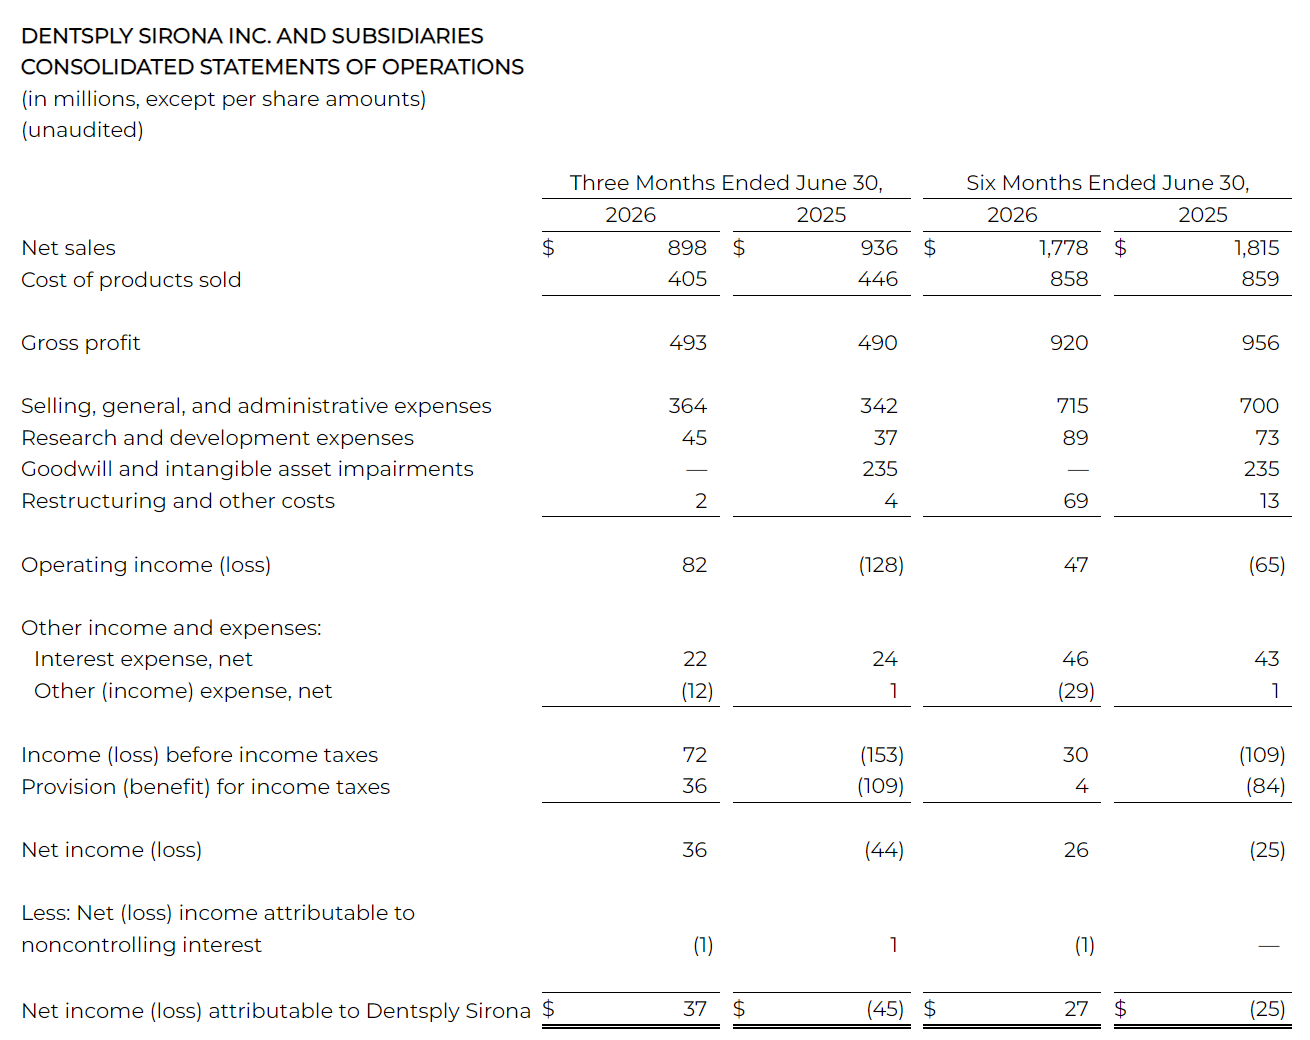
DentalGoodNews|On August 6, 2026, Dentsply Sirona announced its second quarter 2026 results: quarterly revenue of $898 million (approximately RMB 6.062 billion), down 4.1% year-over-year, or 6.3% on a constant currency basis; first-half cumulative revenue of $1.778 billion (approximately RMB 11.996 billion), down approximately 2.0% year-over-year. In terms of profitability, net income attributable to Dentsply Sirona was $37 million (approximately RMB 250 million), compared to a loss of $45 million (approximately RMB 304 million) in the same period last year, with the year-over-year change not meaningful (NM). The prior-year loss was primarily driven by goodwill and intangible asset impairment charges of $235 million (approximately RMB 1.586 billion), with no such impairment recorded in the current period. Excluding related items, adjusted earnings per share for the second quarter was $0.52 (approximately RMB 3.51), down 1.6% year-over-year, with both reported periods at $0.52. From a profitability perspective, gross margin improved year-over-year: GAAP gross margin was 54.9%, up 250 basis points from 52.4% in the prior-year period; adjusted gross margin was 56.4%, up 50 basis points from 55.9% in the prior-year period. Adjusted EBITDA was $190 million (approximately RMB 1.283 billion), with an adjusted EBITDA margin of 21.3%, remaining broadly stable compared to 21.1% in the prior-year period.
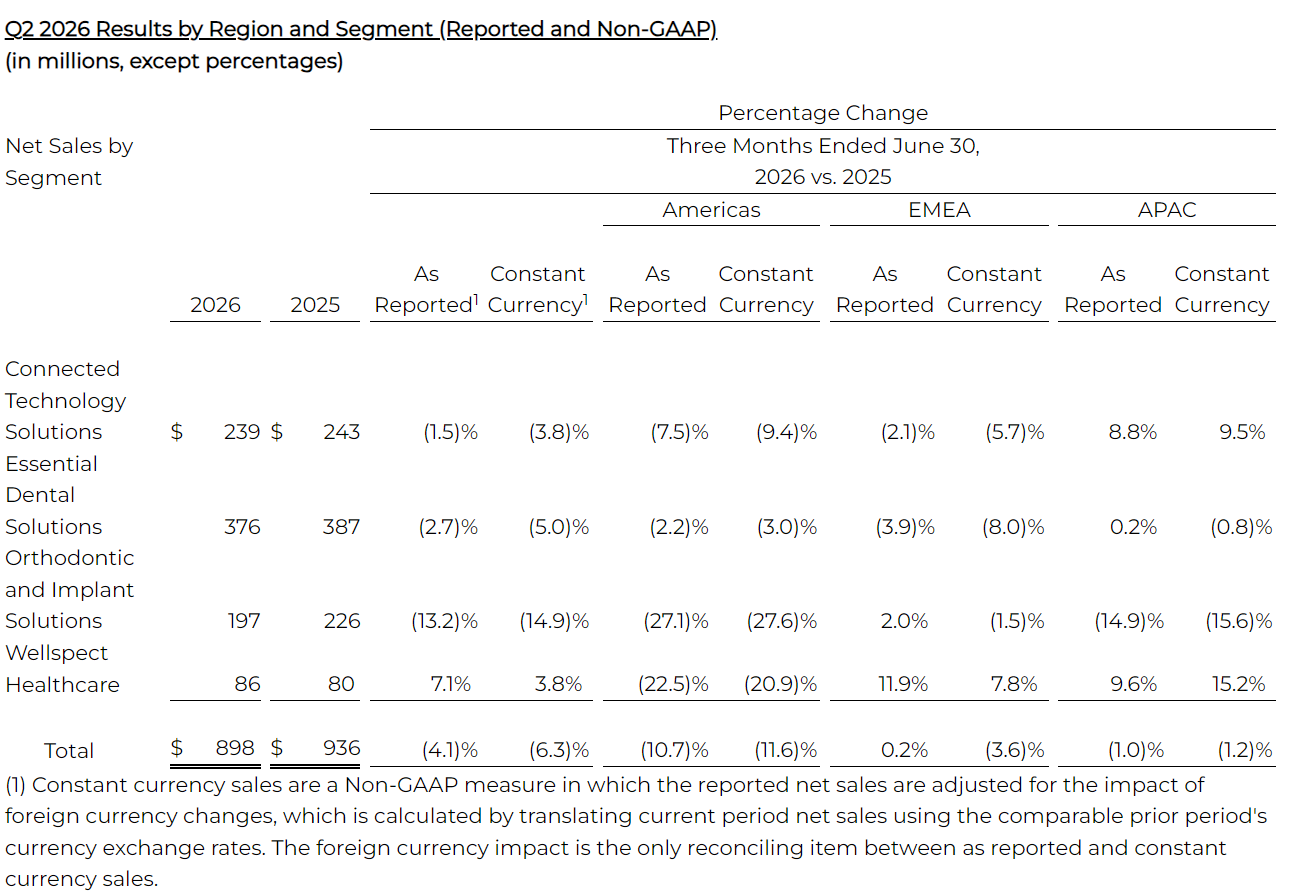
By business structure, Orthodontics and Implant Solutions (OIS) revenue was $197 million (approximately RMB 1.330 billion), down 13.2% year-over-year (down 14.9% on a constant currency basis), representing the largest decline among business segments. By region, the Americas declined 27.1% year-over-year (down 27.6% on a constant currency basis); Asia Pacific declined 14.9% year-over-year (down 15.6% on a constant currency basis); EMEA grew 2.0% year-over-year (down 1.5% on a constant currency basis), making it the only region to achieve year-over-year growth among the three. Within Orthodontics and Implant Solutions, Implant Solutions (IPS) revenue was $157 million (approximately RMB 1.060 billion), down mid-single digits year-over-year, primarily driven by lower premium dental implant volumes in the Americas and Asia Pacific; EMEA implant business achieved mid-single-digit growth, primarily driven by its value implant brand MIS. Orthodontics business SureSmile revenue was $40 million (approximately RMB 270 million), down double digits year-over-year, primarily impacted by Americas performance and the continued impact of the Byte program exit. Essential Dental Solutions (EDS) revenue was $376 million (approximately RMB 2.538 billion), down 2.7% year-over-year (down 5.0% on a constant currency basis), primarily driven by lower volumes in the Americas and EMEA; Asia Pacific EDS remained broadly stable, growing 0.2% year-over-year (down 0.8% on a constant currency basis). Connected Technology Solutions (CTS) revenue was $239 million (approximately RMB 1.613 billion), down 1.5% year-over-year (down 3.8% on a constant currency basis). Among these, Asia Pacific CTS grew 8.8% year-over-year (up 9.5% on a constant currency basis), representing the better-performing region for this business; the conference call disclosed that milling systems within the CAD/CAM business achieved double-digit growth. Regarding the China market, the financial report did not separately disclose sales data for China or Greater China, with the company's current regional segmentation primarily covering the Americas, EMEA, and Asia Pacific. In terms of long-term strategy, CEO Dan Scavilla stated during the Q&A session of the conference call that the company's full-year guidance does not incorporate the material impact of China's Volume-Based Procurement 2.0 (VBP 2.0, second round of centralized procurement). He noted that China is a long-term growth market for the company, and the company is focused on how to further expand its business scale in China, with VBP advancement being one of the important steps to enter this market.
In terms of expenses, selling, general and administrative expenses (SG&A) were $364 million (approximately RMB 2.457 billion), up 6.4% from $342 million (approximately RMB 2.309 billion) in the prior-year period; research and development expenses (R&D) were $45 million (approximately RMB 304 million), up 21.6% from $37 million (approximately RMB 250 million) in the prior-year period. Management indicated that related investments were primarily directed toward sales force building, clinical education, and R&D innovation to support the "Return-to-Growth" action plan. In terms of cash flow, second-quarter operating cash flow was $99 million (approximately RMB 668 million), up approximately 106% year-over-year, primarily driven by approximately $44 million (approximately RMB 297 million) in tariff refunds received and working capital improvements; free cash flow was $55 million (approximately RMB 371 million), compared to $16 million (approximately RMB 108 million) in the prior-year period. Regarding capital allocation, the company repurchased 1.3 million common shares for approximately $12 million (approximately RMB 81 million) during the quarter, marking the first share repurchase since the third quarter of 2024; as of June 30, 2026, the company held cash and cash equivalents of $239 million (approximately RMB 1.613 billion). In terms of outlook, the company maintained its full-year 2026 guidance: revenue of $3.5 billion to $3.6 billion (approximately RMB 23.625 billion to RMB 24.3 billion), adjusted earnings per share of $1.40 to $1.50 (approximately RMB 9.45 to RMB 10.13); tariff refund benefits are not included in the adjusted EPS guidance. Management expects third-quarter revenue to decline sequentially due to seasonal factors, with improvement effects expected to be more reflected in the fourth quarter. Additionally, the company expanded its partnership with Canadian distributor Medline Sinclair to further extend CTS product channel coverage in Canada.
Article classification:
Industry Finance
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|