Envista 2026 Q2: Revenue of $730 Million, Spark Orthodontics Maintains Double-Digit GrowthIssuing time:2026-08-06 14:59
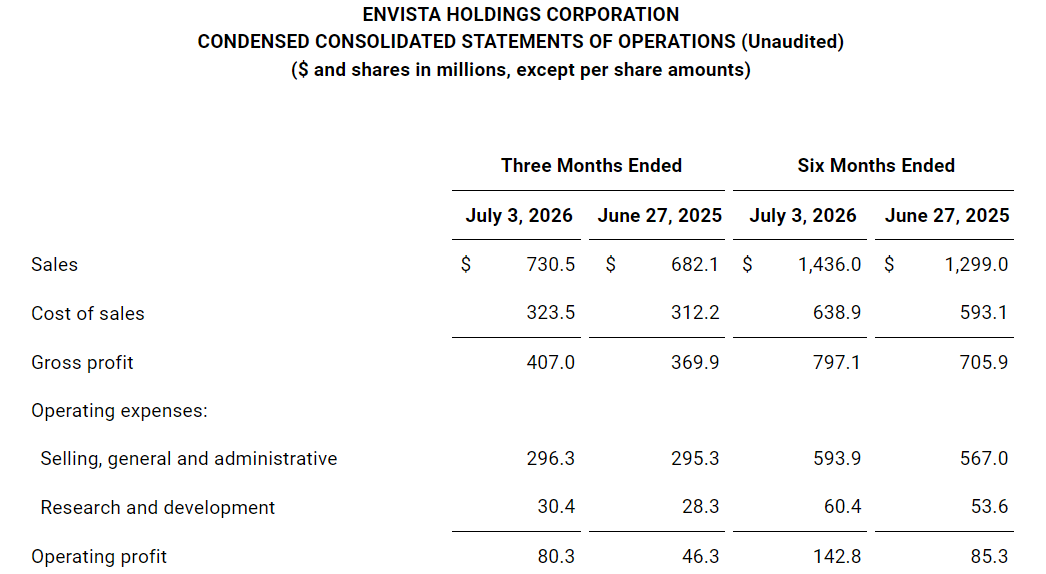
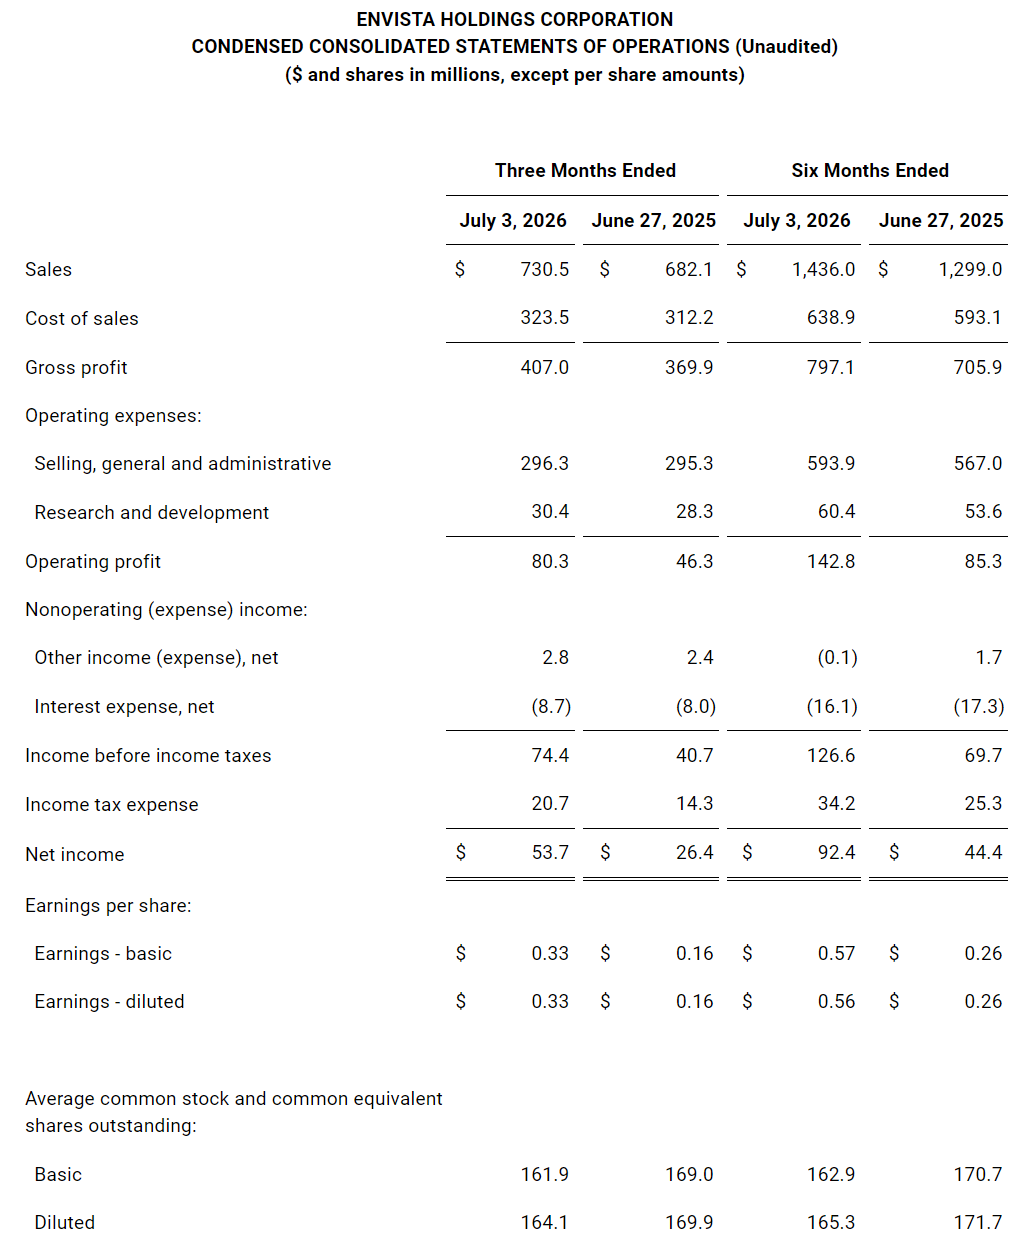
Q2 Revenue $730.5 Million / Spark Orthodontics Business Maintains Double-Digit Growth / Implants, Imaging, and Consumables All Report Positive Growth DentalGoodNews|August 5, 2026 - Envista Holdings Corporation reported its second quarter 2026 results (period ended July 3), with Q2 revenue of $730.5 million (approximately RMB 4.931 billion), up 7.1% year-over-year, and core sales growth of 5.0%. Both business segments delivered positive growth. The company simultaneously raised its full-year guidance, increasing the core sales growth target from 2%-4% to 3.5%-4.5%. On profitability, the company reported revenue of $682.1 million (approximately RMB 4.604 billion) in the same period last year. Gross profit for the quarter was $407.0 million (approximately RMB 2.747 billion), with GAAP gross margin of 55.7%, up 150 basis points year-over-year; adjusted gross margin was 55.1%, up 70 basis points year-over-year. This includes $12.6 million (approximately RMB 85.05 million) in tariff refunds, which the company has excluded from adjusted gross profit, adjusted operating profit, and adjusted EBITDA.
On the profit side, the company reported GAAP operating profit of $80.3 million (approximately RMB 542 million), up 73.4% year-over-year; adjusted operating profit of $94.5 million (approximately RMB 638 million), up 32.9% year-over-year, with adjusted operating margin of 12.9% (versus 10.4% in the prior year period). Net income was $53.7 million (approximately RMB 362 million), up 103.4% year-over-year (versus $26.4 million, approximately RMB 178 million, in the prior year period); adjusted net income was $66.5 million (approximately RMB 449 million), up 52.2% year-over-year. GAAP diluted EPS was $0.33 (approximately RMB 2.23, versus $0.16, approximately RMB 1.08, in the prior year period), and adjusted diluted EPS was $0.41 (approximately RMB 2.77), up 57.7% year-over-year. Adjusted EBITDA was $107.7 million (approximately RMB 727 million), up 27.8% year-over-year, with adjusted EBITDA margin of 14.7%, up 230 basis points from 12.4% in the prior year period.
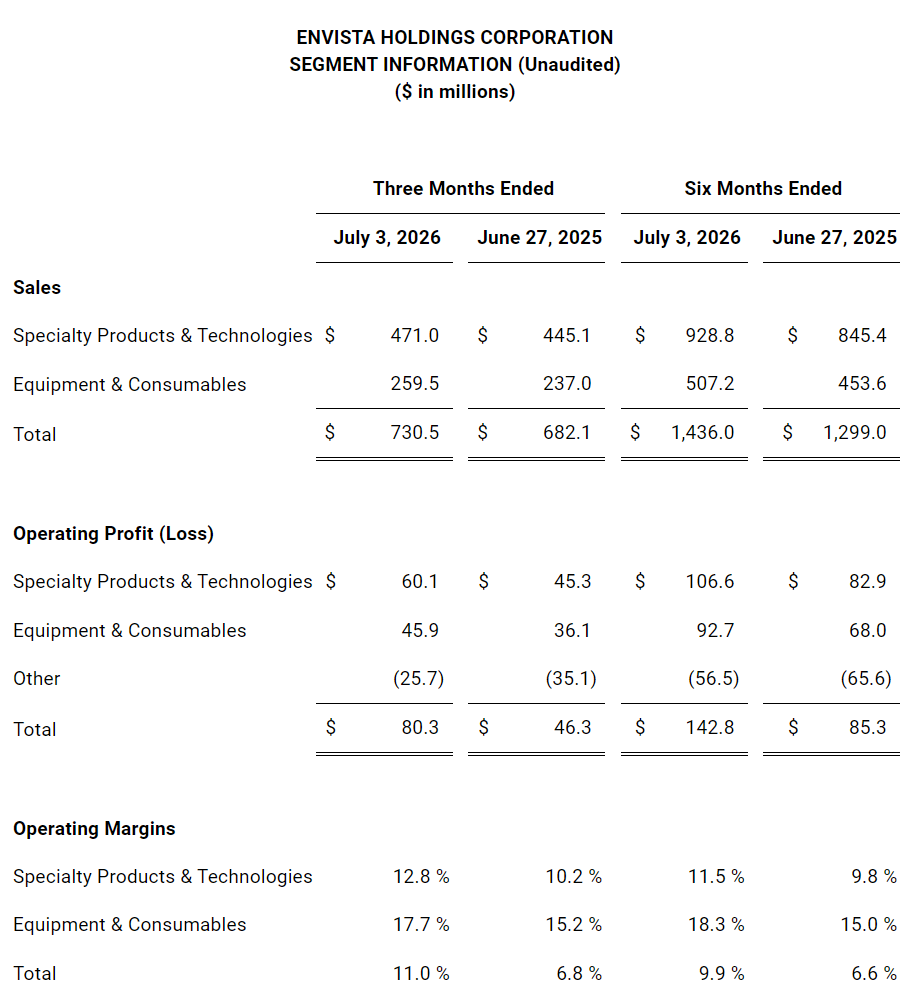
By business segment, both of Envista's operating segments delivered growth. Specialty Products & Technologies (SP&T), which encompasses Nobel Biocare dental implants and Ormco/Spark orthodontics, reported Q2 revenue of $471.0 million (approximately RMB 3.179 billion), up 5.8% year-over-year, with core sales growth of 3.1% (FX impact of -1.9%, M&A contribution of -0.8%). GAAP operating margin was 12.8% (versus 10.2% in the prior year period), and adjusted operating margin was 14.7% (versus 13.5% in the prior year period). Specifically, Spark continued to deliver double-digit growth during the quarter; brackets and archwire business experienced high single-digit decline due to inventory build-up by customers in the prior year period; dental implant business core sales growth was in the low single digits. The other segment, Equipment & Consumables (E&C), which includes DEXIS oral imaging equipment and Kerr consumables, reported Q2 revenue of $259.5 million (approximately RMB 1.752 billion), up 9.5% year-over-year, with core sales growth of 8.5% (FX impact of -1.0%). GAAP operating margin was 17.7% (versus 15.2% in the prior year period), and adjusted operating margin was 20.0% (versus 17.5% in the prior year period). The company noted that E&C has now delivered high single-digit to low double-digit growth for five consecutive quarters, with both consumables and diagnostics businesses achieving high single-digit growth. CEO Paul Keel stated during the earnings call that the segment's growth was driven by market improvement and share gains.
On cash flow, the company reported Q2 operating cash flow of $119.2 million (approximately RMB 805 million) and free cash flow of $105.1 million (approximately RMB 709 million), up from $88.7 million (approximately RMB 599 million) and $76.4 million (approximately RMB 516 million), respectively, in the prior year period. Free cash flow conversion to adjusted net income was 158.0%. During the quarter, the company repurchased approximately 2.4 million shares for approximately $59.0 million (approximately RMB 398 million); as of quarter-end, approximately $283.0 million (approximately RMB 1.910 billion) remained under the repurchase program. For the first half of the year, cumulative revenue was $1.436 billion (approximately RMB 9.693 billion), with adjusted EBITDA of $206.6 million (approximately RMB 1.395 billion) (versus $163.3 million, approximately RMB 1.102 billion, in the prior year period). Q2 R&D spending was $30.4 million (approximately RMB 205 million), up 7.4% year-over-year (versus $28.3 million, approximately RMB 191 million, in the prior year period), representing an R&D expense ratio of 4.2%.
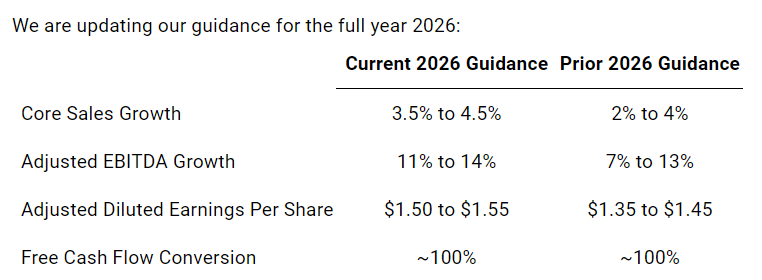
Based on improved business performance, the company further raised its full-year 2026 outlook: core sales growth target increased from 2%-4% to 3.5%-4.5%; adjusted EBITDA growth target increased from 7%-13% to 11%-14%; adjusted diluted EPS increased from $1.35-$1.45 (approximately RMB 9.11-9.79) to $1.50-$1.55 (approximately RMB 10.13-10.46); free cash flow conversion target remains at approximately 100%.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|