Solventum 2026 Q2: Dental Business Revenue Reaches $396 Million, Up 17.0% Year-over-YearIssuing time:2026-08-06 11:50
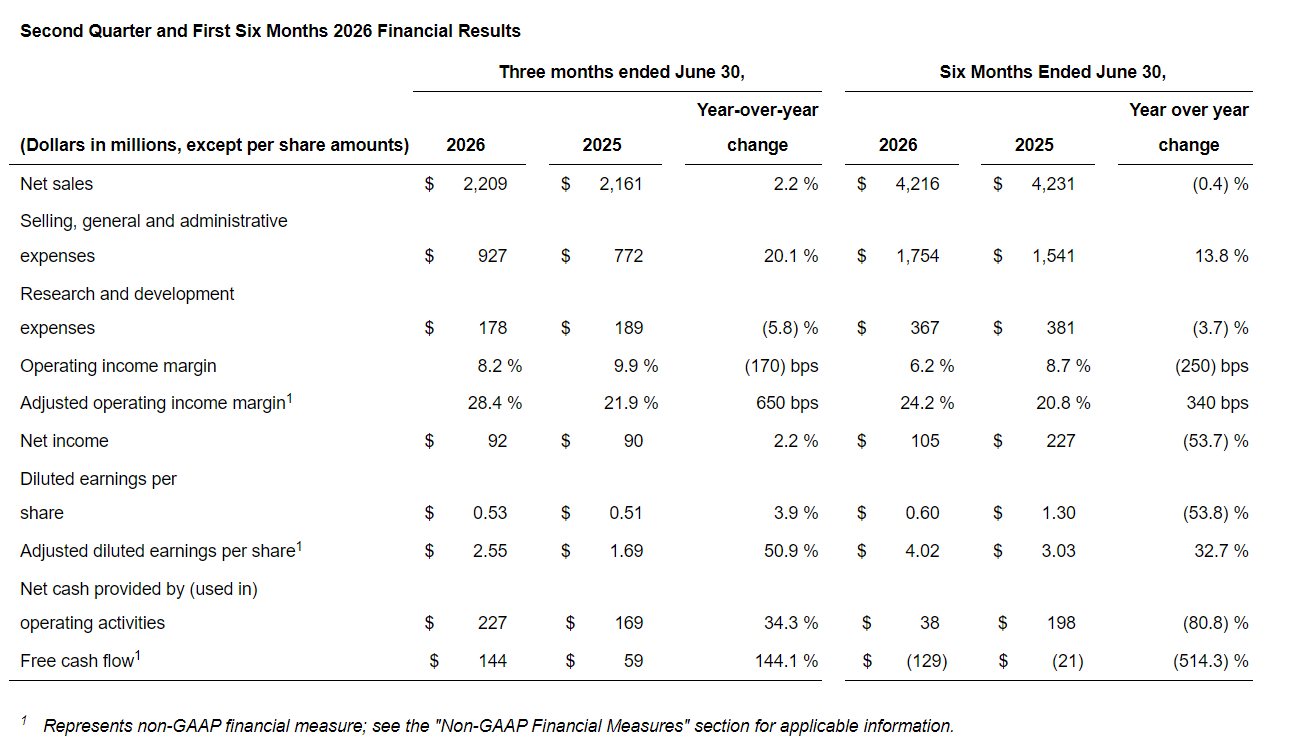
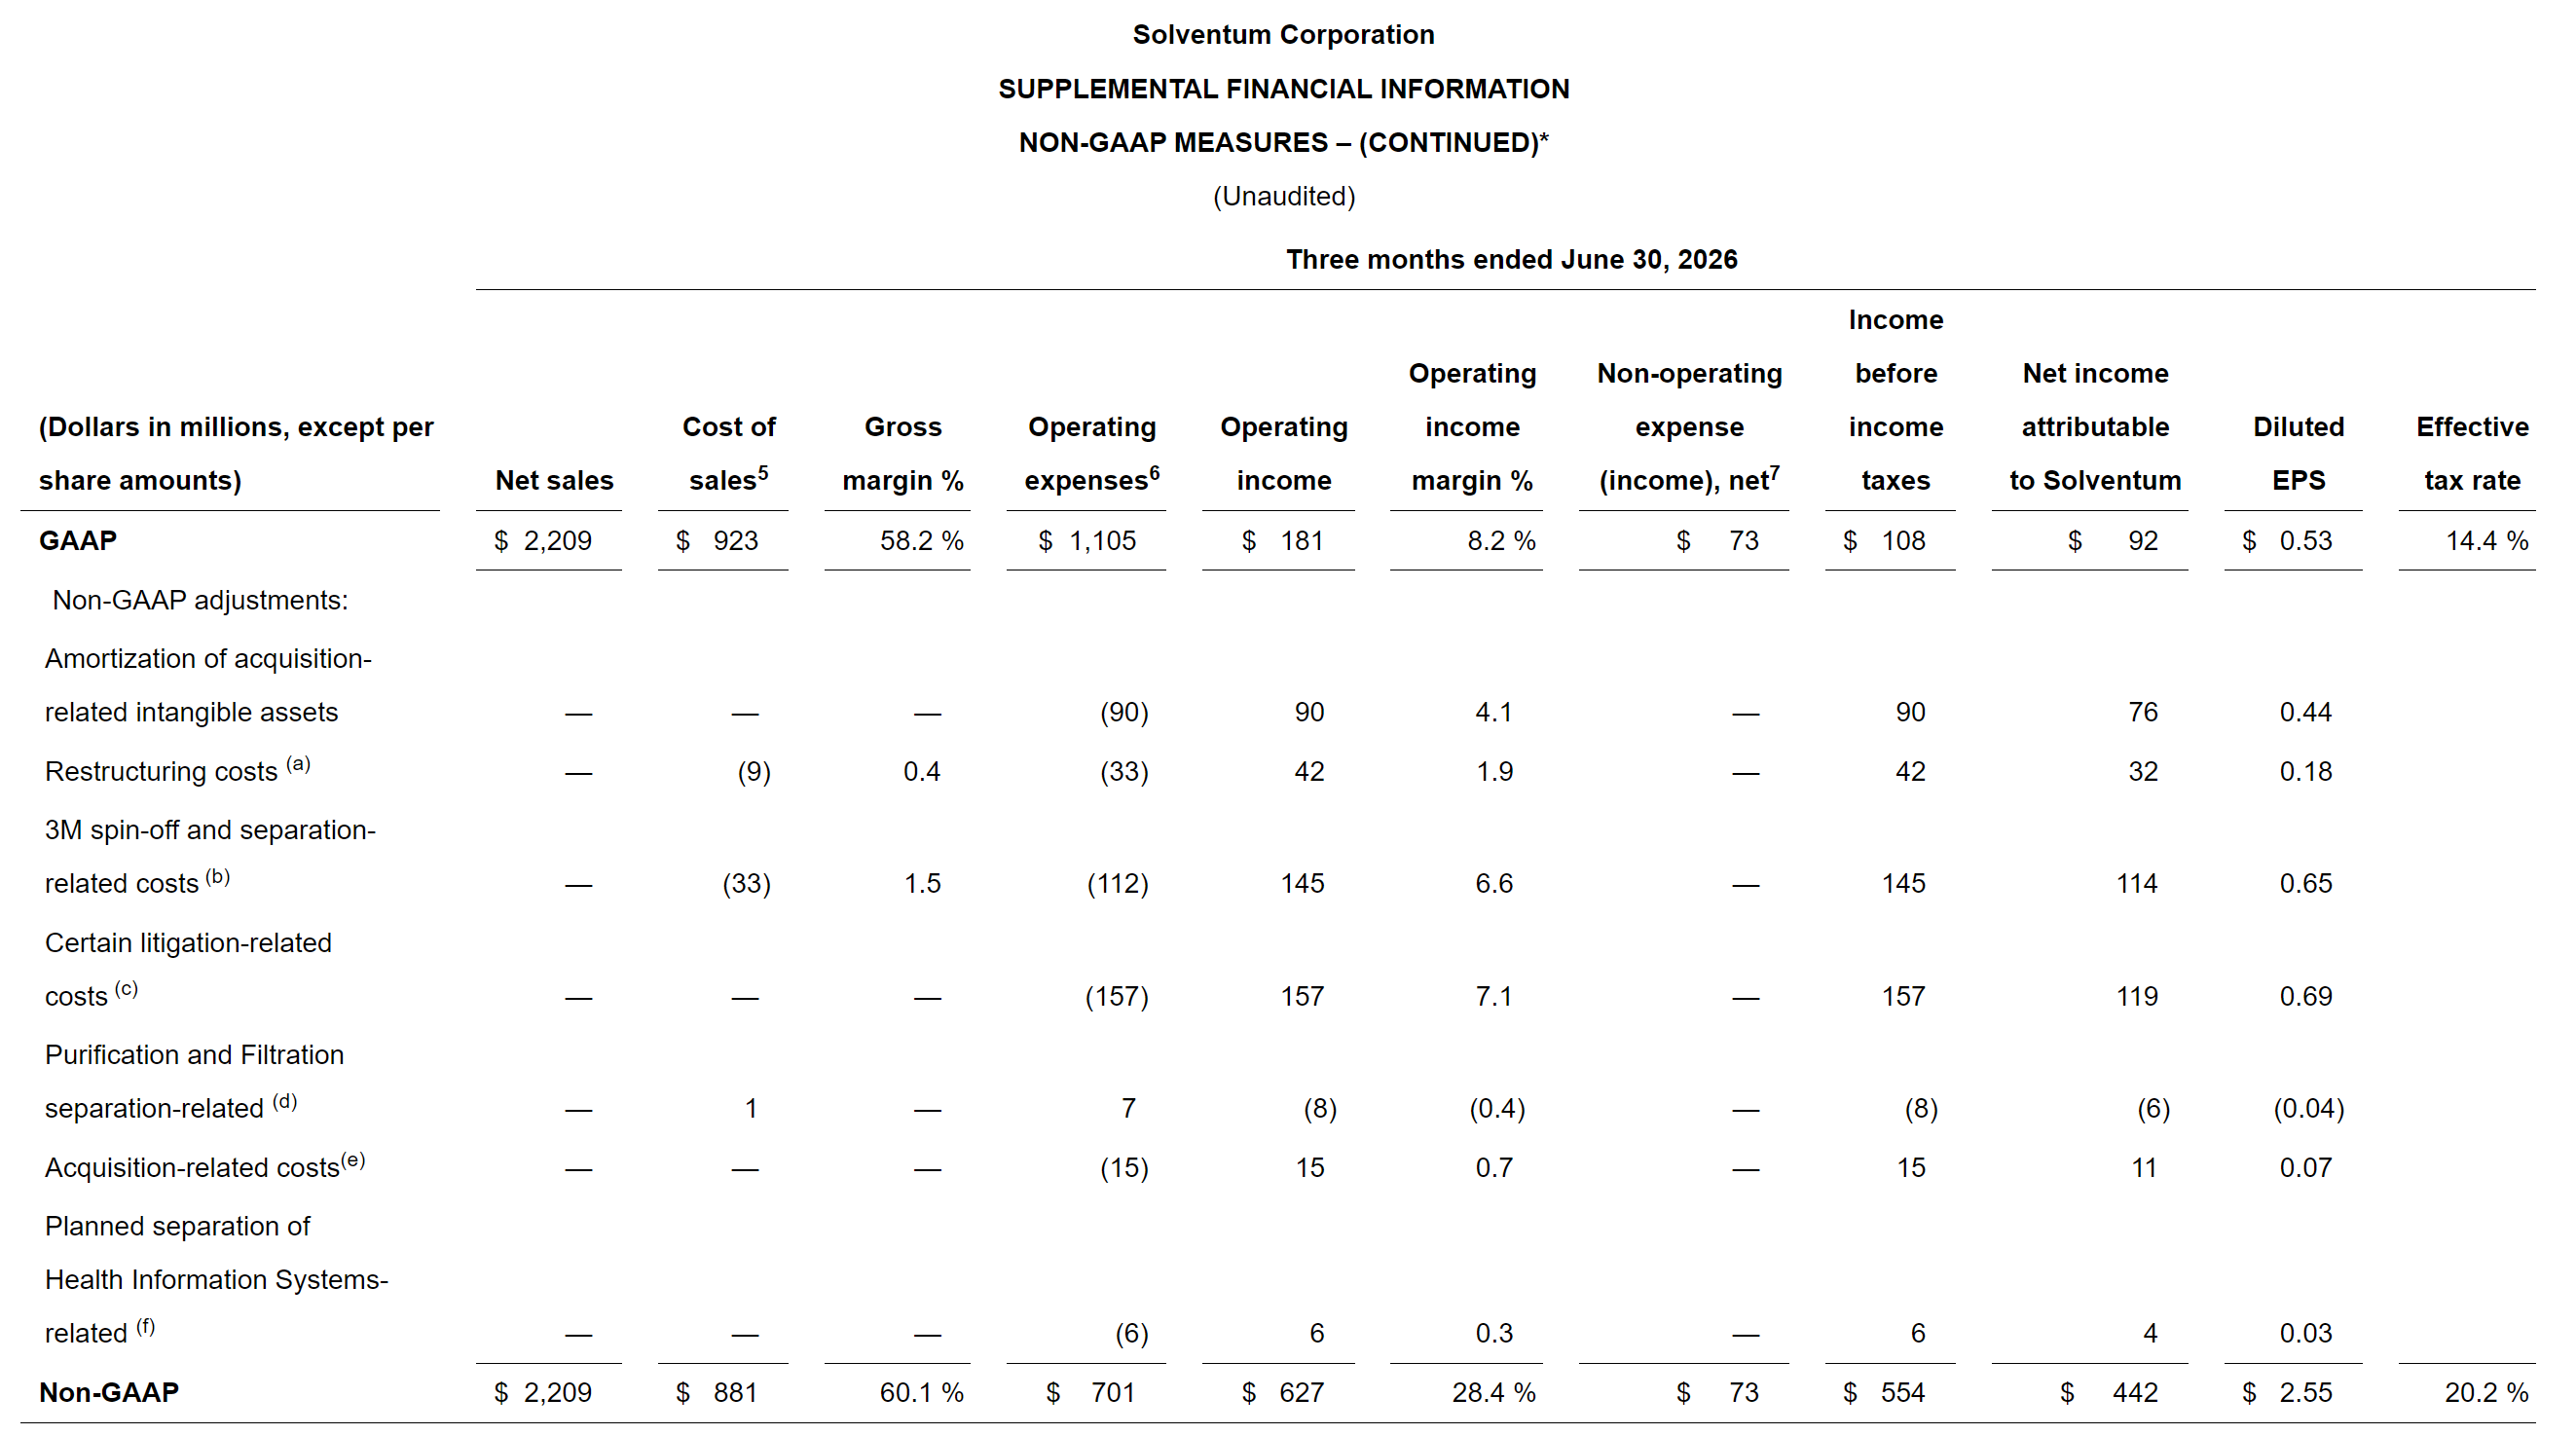
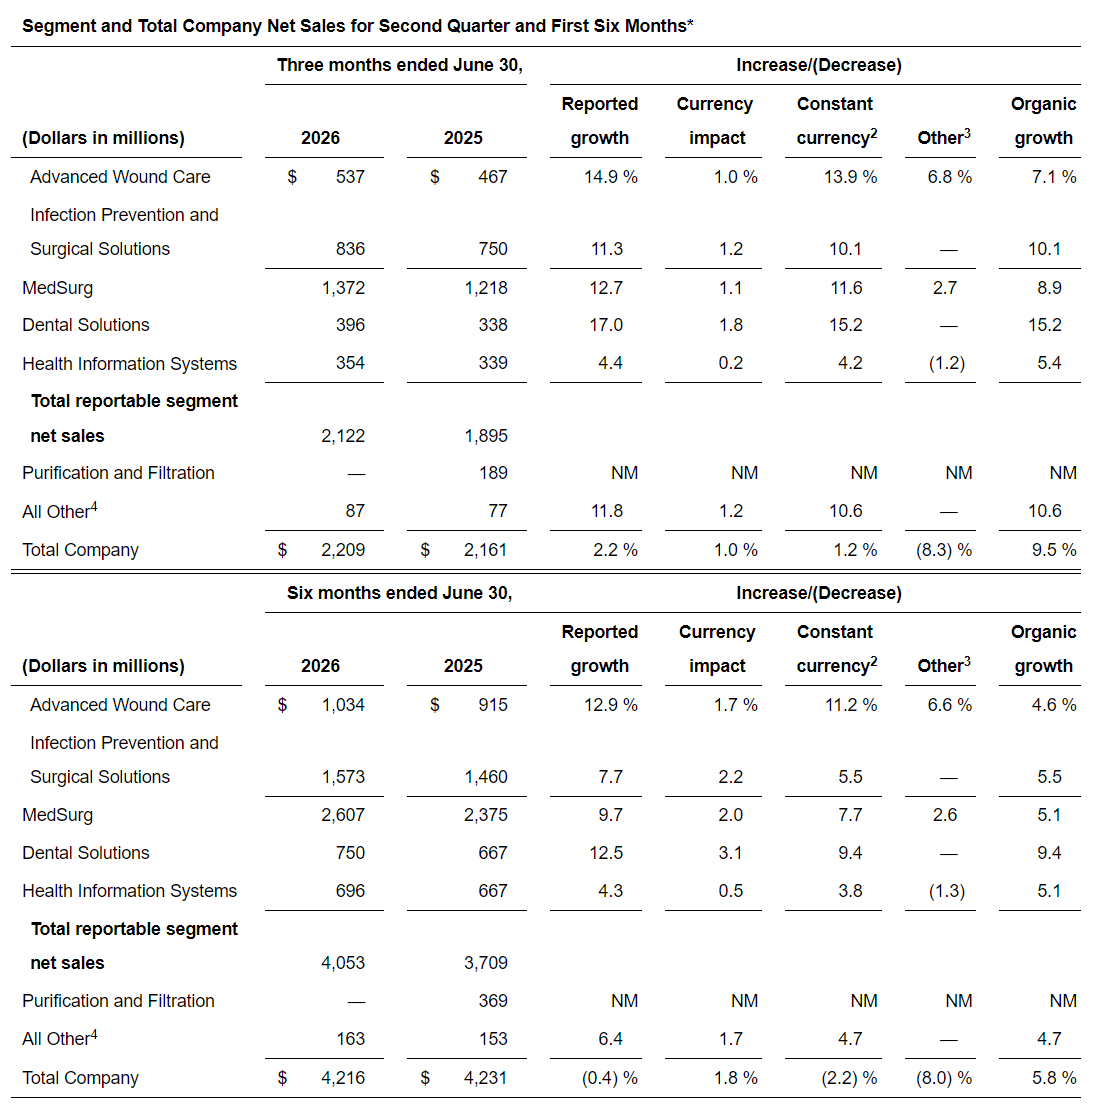
Planned Spin-off of Health Information Systems Business / Adjusted EPS Up 50.9% / Dental Business Revenue Up 17.0% YoY DentalGoodNews|August 5, 2026 - Solventum Corporation | NYSE: SOLV released its Q2 2026 financial results. During the reporting period, the company achieved revenue of $2.209 billion (approximately RMB 14.911 billion), up 2.2% year-over-year, with organic growth of 9.5%. Net Profit Attributable to Shareholders of the Parent Company was $92 million (approximately RMB 621 million), up 2.2% year-over-year. In terms of financial performance, under Non-Generally Accepted Accounting Principles (Non-GAAP)|Generally Accepted Accounting Principles, Solventum's adjusted Net Profit Attributable to Shareholders of the Parent Company for Q2 was $442 million (approximately RMB 2.984 billion, excluding spin-off costs, legal expenses, and acquisition-related impacts), representing an increase of approximately 49.3% from $296 million (approximately RMB 1.998 billion) in the same period last year. Adjusted Operating Margin reached 28.4%, up 650 basis points from 21.9% in the same period last year. Adjusted diluted earnings per share (EPS) was $2.55 (approximately RMB 17.21), up 50.9% year-over-year (with ERP premium orders contributing approximately $0.34 (approximately RMB 2.30) per share and IEEPA tariff rebates contributing approximately $0.48 (approximately RMB 3.24) per share; excluding these two one-time factors, adjusted EPS was approximately $1.73 (approximately RMB 11.68), still exceeding expectations).
The company noted that profit growth was primarily driven by gross margin improvements from IEEPA tariff rebates, as well as the timing benefit from customers placing orders ahead of the ERP system transition. Additionally, under Generally Accepted Accounting Principles|GAAP, Operating Margin declined from 9.9% in the same period last year to 8.2% (down 170 basis points), mainly due to increased spin-off-related costs and legal expenses. The Dental Solutions segment achieved revenue of $396 million (approximately RMB 2.673 billion) in the quarter, up 17.0% year-over-year, with organic growth of 15.2% (of which customer pre-stocking ahead of the ERP system transition contributed approximately 10 percentage points; excluding this, underlying organic growth was approximately 5%). The segment's Operating Margin reached 33.0%, up 450 basis points from 28.5% in the same period last year. The company stated that the segment's growth was primarily driven by sales volume and product mix optimization. On a cumulative basis for the first half of the year (January-June 2026), the Dental Solutions segment achieved revenue of $750 million (approximately RMB 5.063 billion), up 12.5% from $667 million (approximately RMB 4.502 billion) in the same period last year, with organic growth of 9.4% (with currency contributing 3.1 percentage points).
In terms of cash flow and guidance, the company's operating cash flow for Q2 was $227 million (approximately RMB 1.532 billion), with free cash flow of $144 million (approximately RMB 972 million), up significantly by 144.1% year-over-year. The company stated that cash flow performance was "ahead of expectations," primarily related to factors such as tax payment timing differences and insurance reimbursements. Additionally, the company repurchased approximately 4 million shares in Q2, totaling $288 million (approximately RMB 1.944 billion); cumulative repurchases over the first two quarters reached $355 million (approximately RMB 2.396 billion), completing more than one-third of the $1 billion (approximately RMB 6.750 billion) share repurchase program. Based on the quarterly results, Solventum raised its full-year 2026 guidance: organic sales growth target was raised to 2.5%-3.0% (3.5%-4.0% after excluding the approximately 100 basis point impact from SKU exits), adjusted EPS guidance range was raised to $7.10-$7.20 (approximately RMB 47.93-48.60), and free cash flow target was set at $200 million-$300 million (approximately RMB 1.350 billion-2.025 billion). CFO Wayde McMillan noted during the earnings call that approximately $125 million (approximately RMB 844 million) of ERP premium orders in Q2 would primarily reverse in Q3, with Q3 organic growth expected to turn to -3% to -4%. Additionally, Solventum announced that, as part of its transformation strategic investment portfolio optimization phase, the company plans to spin off its Health Information Systems (HIS) business segment. CEO Bryan Hanson stated that the spin-off is designed to enable Solventum to focus on advancing its Medical Surgical and Dental Solutions businesses, while allowing HIS to accelerate its own strategic initiatives as an independent entity. The spin-off is expected to be completed within 12 to 18 months, with Morgan Stanley and Goldman Sachs serving as financial advisors.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|