Envista 2026 Q1: Sales Revenue of $706 Million, Core Revenue Up 9.5% Year-over-Year [SOURCE] Envista reported sales revenue of $706 million for the first quarter of 2026, with core revenue i…Issuing time:2026-05-08 17:49
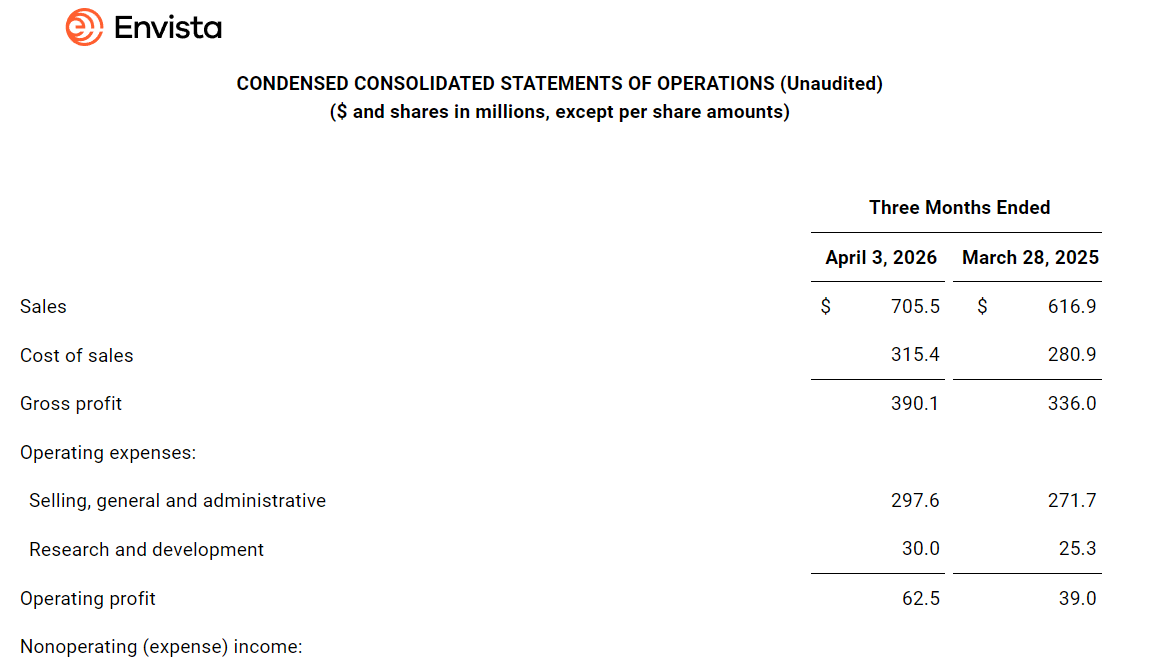
DentalGoodNews|On May 6, 2026, Envista Holdings Corporation released its first-quarter 2026 earnings report. The report data shows that the company's single-quarter sales for the first quarter were $705.5 million (approximately RMB 4.804 billion), a year-over-year increase of 14.4%, with core sales growth of 9.5% excluding the impact of foreign exchange and acquisitions; adjusted diluted earnings per share were $0.36, up 50.0% year-over-year; adjusted EBITDA margin was 14.0%, an improvement of 120 basis points from 12.8% in the same period of 2025. CEO Paul Keel stated that all major businesses achieved growth in 2026, with core revenue growth of 9.5% translating into a 25% increase in adjusted EBITDA and a 50% increase in earnings per share.
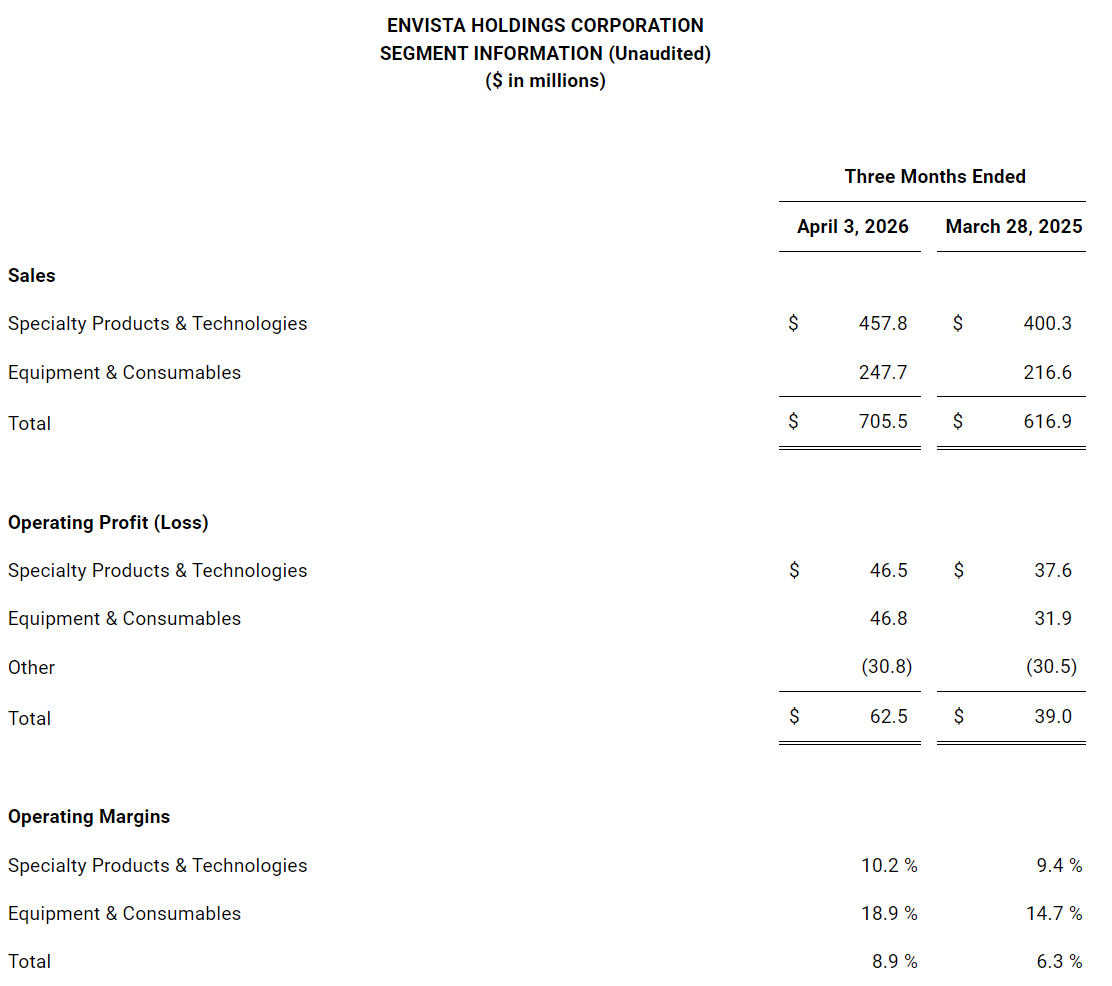
By business segment, the Specialty Products & Technologies segment (covering Nobel Biocare and Implant Direct dental implants, as well as Ormco and Spark clear aligners and other orthodontic businesses) achieved sales of $457.8 million (approximately RMB 3.118 billion), a year-over-year increase of 14.4%, with core growth of 8.4% and an adjusted operating margin of 14.5% (14.1% in Q1 2025). Within this segment, both Spark and B&W achieved double-digit growth, while Implants showed mid-single-digit growth outside of China, with a short-term decline in the Chinese market to align with Volume-Based Procurement (VBP) policies. The Equipment & Consumables segment (covering DEXIS imaging diagnostics and Kerr consumables) achieved sales of $247.7 million (approximately RMB 1.687 billion), a year-over-year increase of 14.4%, with core growth of 11.5% and an adjusted operating margin of 21.0% (18.1% in Q1 2025). Both diagnostic and consumable products achieved growth in North America and Western Europe.
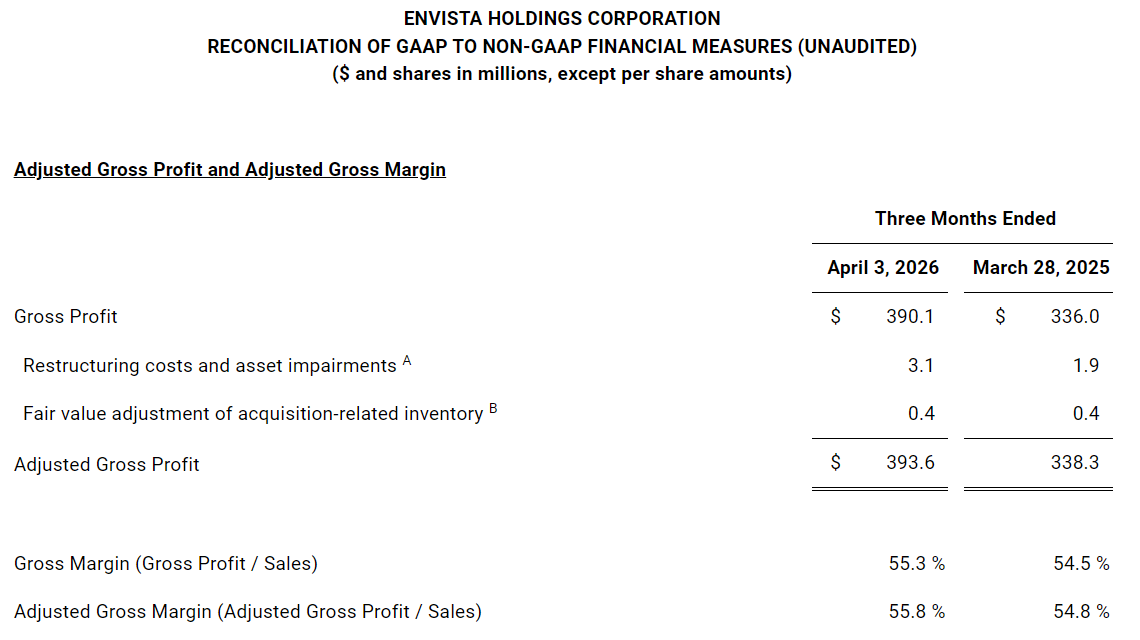
In terms of profitability, GAAP gross margin was 55.3% (54.5% in Q1 2025), and adjusted gross margin was 55.8% (54.8% in Q1 2025), an improvement of approximately 100 basis points. The gross margin improvement was primarily attributed to the ongoing optimization of the Envista Business System (EBS). R&D expenses were $30 million (approximately RMB 204 million). The company stated that R&D and sales and marketing investments achieved double-digit growth in the quarter.
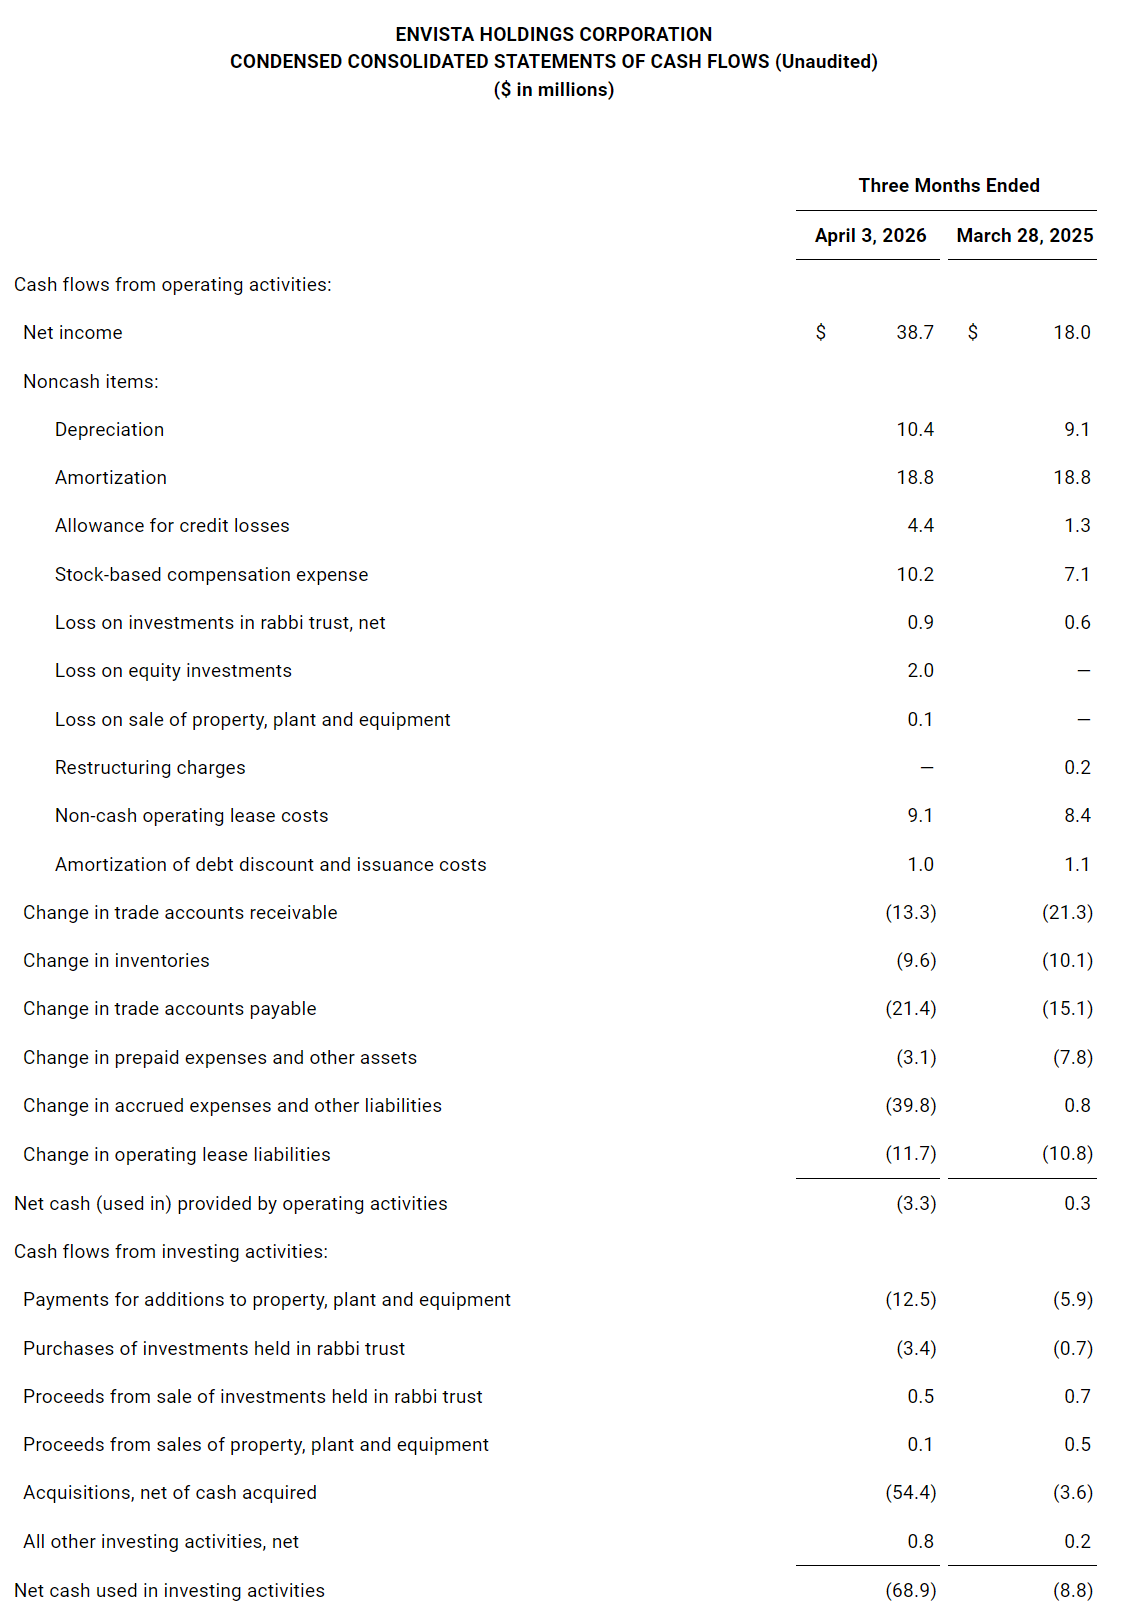
In terms of cash flow, net cash outflow from operating activities in the quarter was $3.3 million (approximately RMB 22.47 million) (net inflow of $0.3 million in Q1 2025), capital expenditures were $12.5 million (approximately RMB 85.13 million) (Q1 2025: $5.9 million), and M&A expenditures were $54.4 million (approximately RMB 371 million). Cash and cash equivalents at the end of the period were $1.0828 billion (approximately RMB 7.374 billion) (end of 2025: $1.2117 billion, approximately RMB 8.252 billion). During the quarter ending April 3, 2026, the company repurchased a total of 1.6 million shares, amounting to approximately $43 million (approximately RMB 293 million). At the end of the quarter, the company had approximately $41 million remaining under its existing repurchase authorization. The Board of Directors authorized a new $300 million (approximately RMB 2.043 billion) share repurchase program, effective through December 31, 2029. For 2026, the company expects core sales growth of 2%-4%, adjusted EBITDA growth of 7%-13%, adjusted diluted earnings per share of $1.35-$1.45 (approximately RMB 9.19-9.87), and a free cash flow conversion rate of approximately 100%.
Article classification:
Industry Finance
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|