Lantian Dental 2025 Annual Report: Revenue of 375 Million Yuan, Net Profit Up 124.24% Year-on-YearIssuing time:2026-04-28 10:39
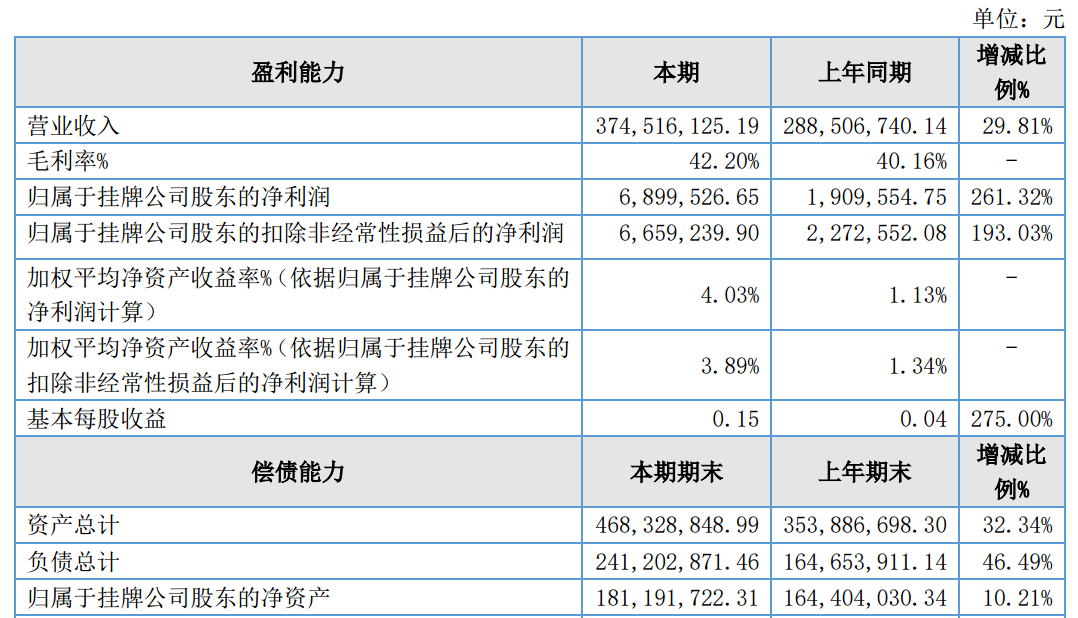
DentalGoodNews|On April 27, 2026, Guangxi Lantian Stomatological Hospital Group Co.,Ltd (hereinafter referred to as "Lantian Dental") released its 2025 annual report. During the reporting period, the company achieved total operating revenue of RMB 375 million, up 29.81% year-on-year; net profit of RMB 11.90 million, up 124.24%; net profit attributable to shareholders of the listed company of RMB 6.90 million, up 261.32%; and Non-GAAP Net Profit attributable to shareholders of the listed company of RMB 6.65 million, up 192.60% year-on-year. The company stated that the full-year 2025 performance growth was primarily driven by a recovery in market demand, improved customer acquisition capabilities at stores that have been operational for nearly three years, online and offline marketing promotions, and the revenue and profit contributions from the acquisition of Anhui Beijie Medical Technology Co., Ltd. (hereinafter referred to as "Beijie Medical") (1 dental hospital and 4 dental clinics).
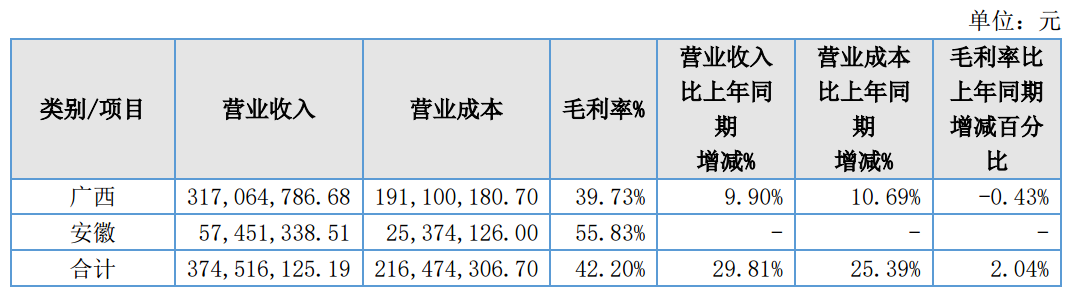
During the reporting period, Lantian Dental announced the completion of the acquisition of a 55% equity stake in Beijie Medical, marking a key step in its nationwide expansion strategy. After consolidation, the company added RMB 57.45 million in revenue from the Anhui region, where the gross margin reached 55.83%, higher than the company's overall average of 42.20%. This acquisition also generated goodwill of RMB 8.44 million.
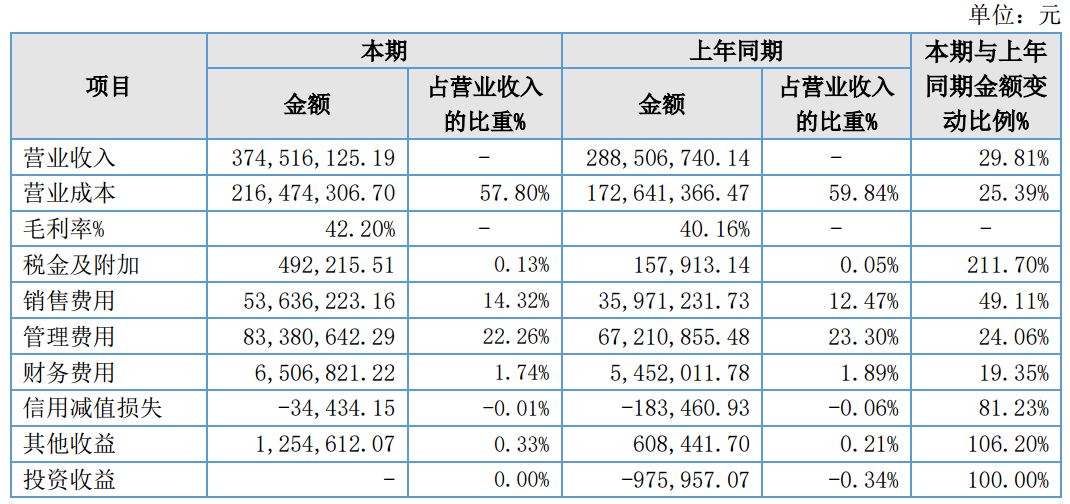
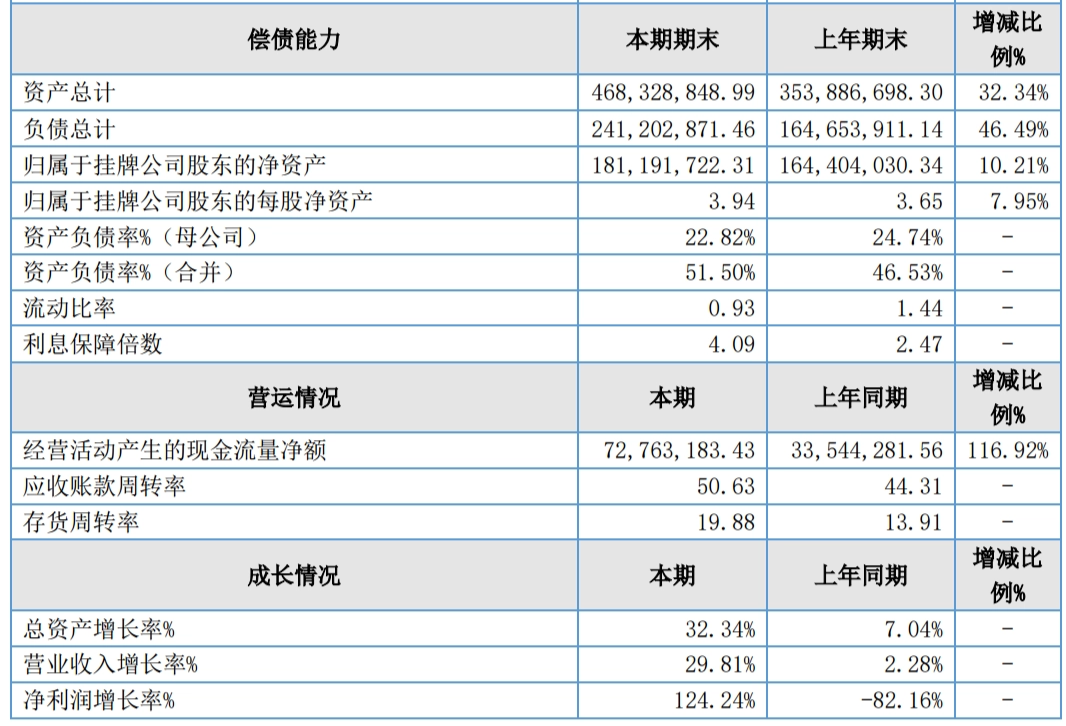
In terms of financial structure, the company's gross margin for 2025 was 42.20%, up 2.04 percentage points year-on-year. Selling expenses increased by 49.11% to RMB 53.64 million, driven by the consolidation of Beijie Medical, higher online advertising and promotional expenses, and increased sales personnel compensation compared to the same period last year. As of the end of the period, the company's total assets were RMB 468 million, up 32.34% from the beginning of the year; total liabilities were RMB 241 million, with a debt-to-asset ratio (consolidated) of 51.50%.
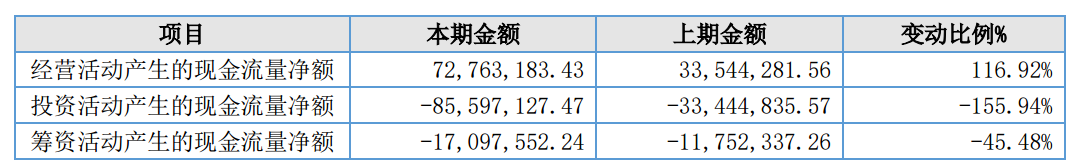
In terms of cash flow, net cash flow from operating activities during the reporting period was RMB 72.76 million, up 116.92% year-on-year; net cash flow from investing activities was RMB -85.60 million, down 155.94%; and net cash flow from financing activities was RMB -17.10 million, down 45.48%. Among these, the increase in net Operating Cash Flow was mainly driven by higher revenue, but it differed from net profit, primarily due to increased operating expenses such as staffing costs from newly established and under-construction facilities, as well as rising non-cash expenses like depreciation and amortization from additional stores. The decline in net cash flow from investing activities was mainly due to store expansion and upgrades, the acquisition of Anhui Beijie Medical equity, and the purchase of the Yulin Sofitel podium property and the Liuzhou Luzhai clinic property. The decrease in net cash flow from financing activities was mainly due to the repayment of some bank loans. In terms of expansion, the company opened new Du'an and Luzhai clinics within Guangxi and completed the expansion and upgrade of Nanning Jinchuan, Nanning Jiangnan, Liuzhou clinics, and Wuzhou hospital; outside the region, it achieved cross-provincial expansion through the controlling stake in Beijie Medical. Additionally, the company disclosed in the report that construction has commenced on new facilities in five cities: Liuzhou, Laibin, Binyang, Pingnan, and Lujiang in Anhui.
Article classification:
Industry Finance
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|