Dencare: E-commerce model revenue reaches 588 million yuan in 2025, a year-on-year increase of 22.33%Issuing time:2026-04-23 12:16
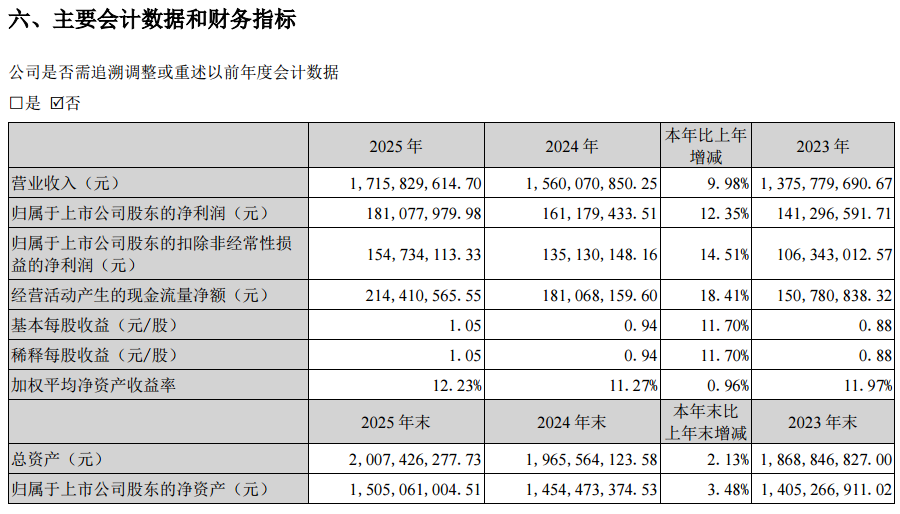
Q1 2026 Revenue and Profit Both Increase / 2025 Net Profit Attributable to Shareholders of the Parent Company Up 12.35% Year-on-Year / 2025 E-commerce Model Revenue Up 22.33% Year-on-Year DentalGoodNews|Dencare released its 2025 Annual Report and 2026 First Quarter Report. According to the report data, in 2025, the company achieved operating revenue of 1.716 billion yuan, a year-on-year increase of 9.98%; net profit attributable to shareholders of the listed company was 181 million yuan, a year-on-year increase of 12.35%; net profit attributable to shareholders of the parent company after deducting non-recurring gains and losses was 155 million yuan, a year-on-year increase of 14.51%; basic earnings per share were 1.05 yuan, a year-on-year increase of 11.70%.
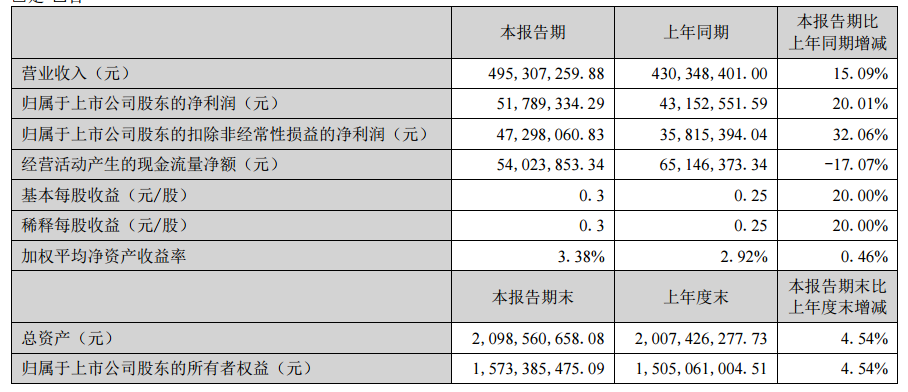
In the single quarter of Q1 2026, operating revenue reached 495 million yuan, a year-on-year increase of 15.09%; net profit attributable to shareholders of the listed company was 52 million yuan, a year-on-year increase of 20.01%; net profit attributable to shareholders of the parent company after deducting non-recurring gains and losses was 47 million yuan, a year-on-year increase of 32.06%; basic earnings per share were 0.3 yuan, a year-on-year increase of 20.00%. The report points out that one of the direct drivers for the improvement in profitability in Q1 2026 was the significant narrowing of Asset Impairment Loss: the Asset Impairment Loss for Q1 was only 168,700 yuan, a decrease of 96.28% compared to 4.5387 million yuan in the same period last year. The main reason was the heavier inventory structure and higher provision for price decline in the same period last year, while the inventory structure in Q1 has been optimized.
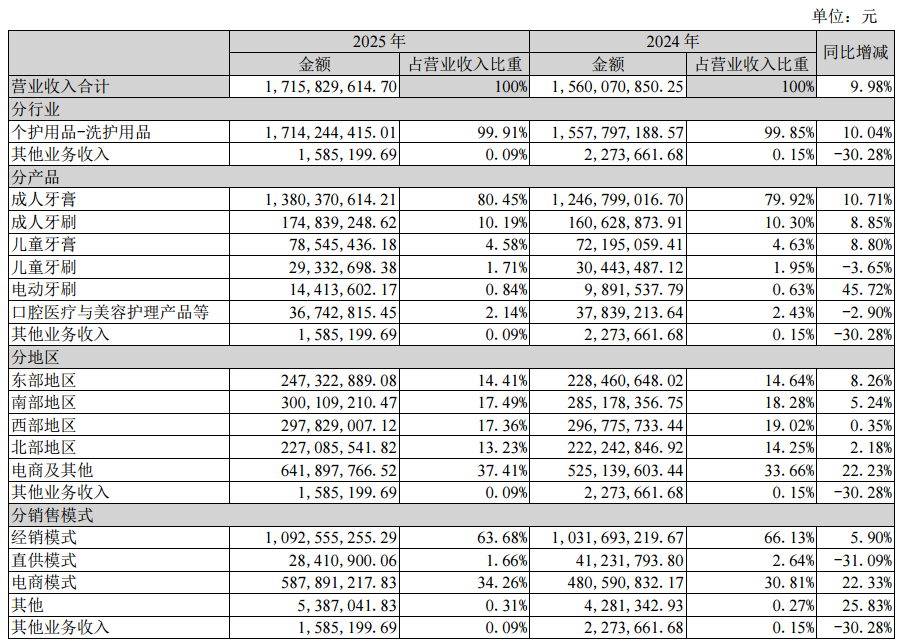
The report shows that in 2025, its market retail sales share for adult toothpaste and children's toothpaste both ranked third in the industry; toothbrush market performance was outstanding, with its market retail sales share rising to second in the industry; children's toothbrushes maintained their leading position as number one in the industry. Report data shows that in 2025, adult toothpaste revenue was 1.380 billion yuan, a year-on-year increase of 10.71%, accounting for 80.45% of total revenue; children's toothpaste revenue was 79 million yuan, a year-on-year increase of 8.80%, accounting for 4.58% of total revenue; adult toothbrush revenue was 175 million yuan, a year-on-year increase of 8.85%, accounting for 10.19% of total revenue; children's toothbrush revenue was 29 million yuan, a year-on-year decrease of 3.65%, accounting for 1.17% of total revenue; Electric Toothbrush revenue was 14 million yuan, a year-on-year increase of 45.72%, accounting for 0.84% of total revenue. Furthermore, the report notes that its medical research series of high-end toothpaste formed a dual-hit product matrix, driving sales of the medical research platform to double. According to a previous report by DGN, Dencare achieved revenue of 1.560 billion yuan in 2024, with the e-commerce model showing significant growth. Report data shows that in 2025, its e-commerce model continued to grow, achieving revenue of 588 million yuan, a year-on-year increase of 22.33%, with its share of total revenue increasing from 30.81% the previous year to 34.26%. Additionally, the distribution model remained the main source of income, achieving revenue of 1.093 billion yuan, a year-on-year increase of 5.90%, with its share of total revenue decreasing from 66.13% the previous year to 63.68%.
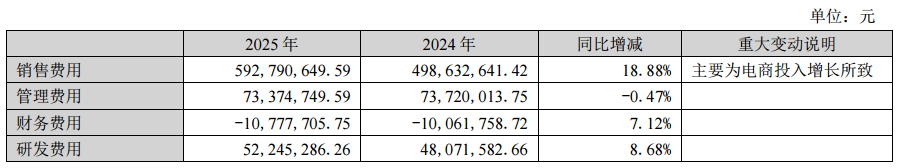
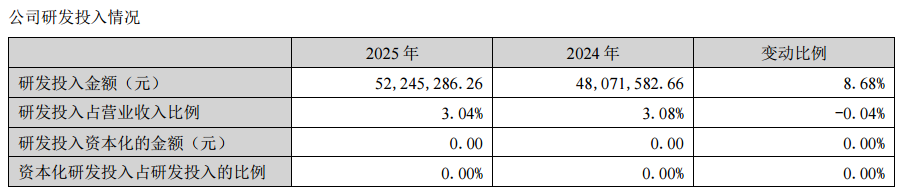
In 2025, the company's R&D investment was 52 million yuan, a year-on-year increase of 8.68%. R&D investment accounted for 3.04% of operating revenue, a decrease of 0.04 percentage points compared to 2024. As of December 31, 2025, the company had obtained over 270 domestic authorized patents, including technologies such as dual anti-sensitivity and bioactive glass-ceramic specialized repair.
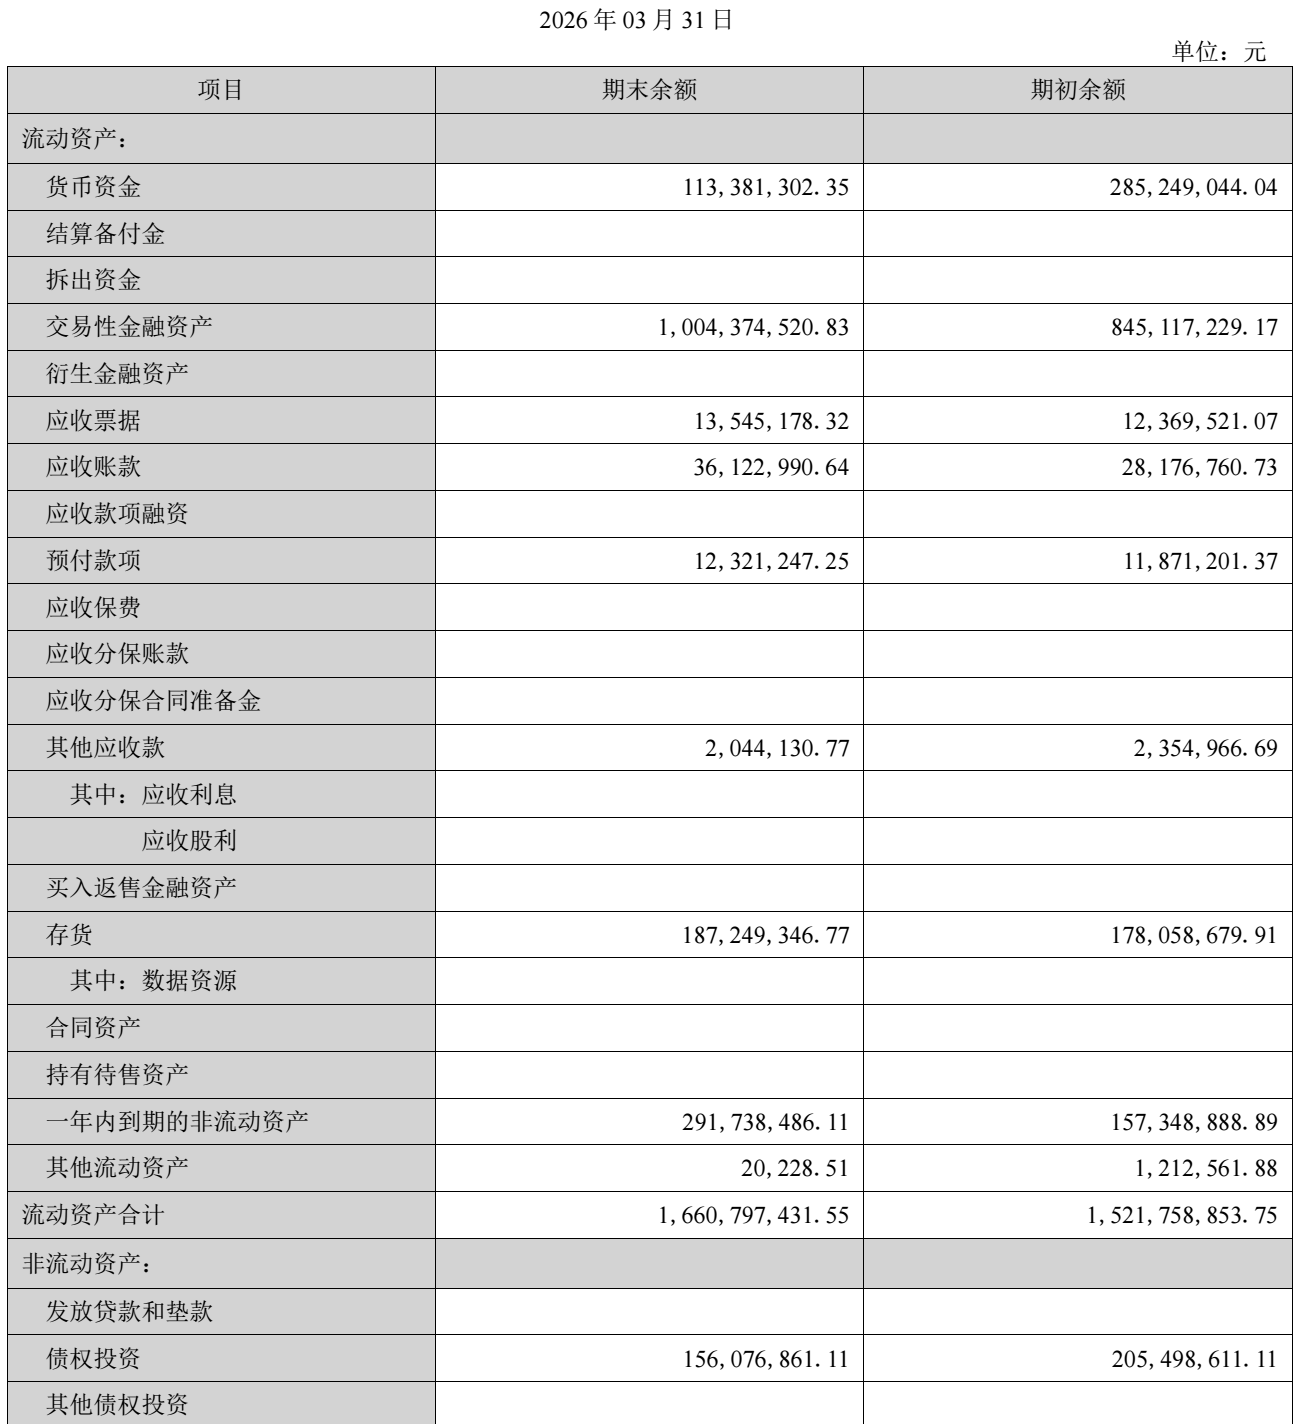
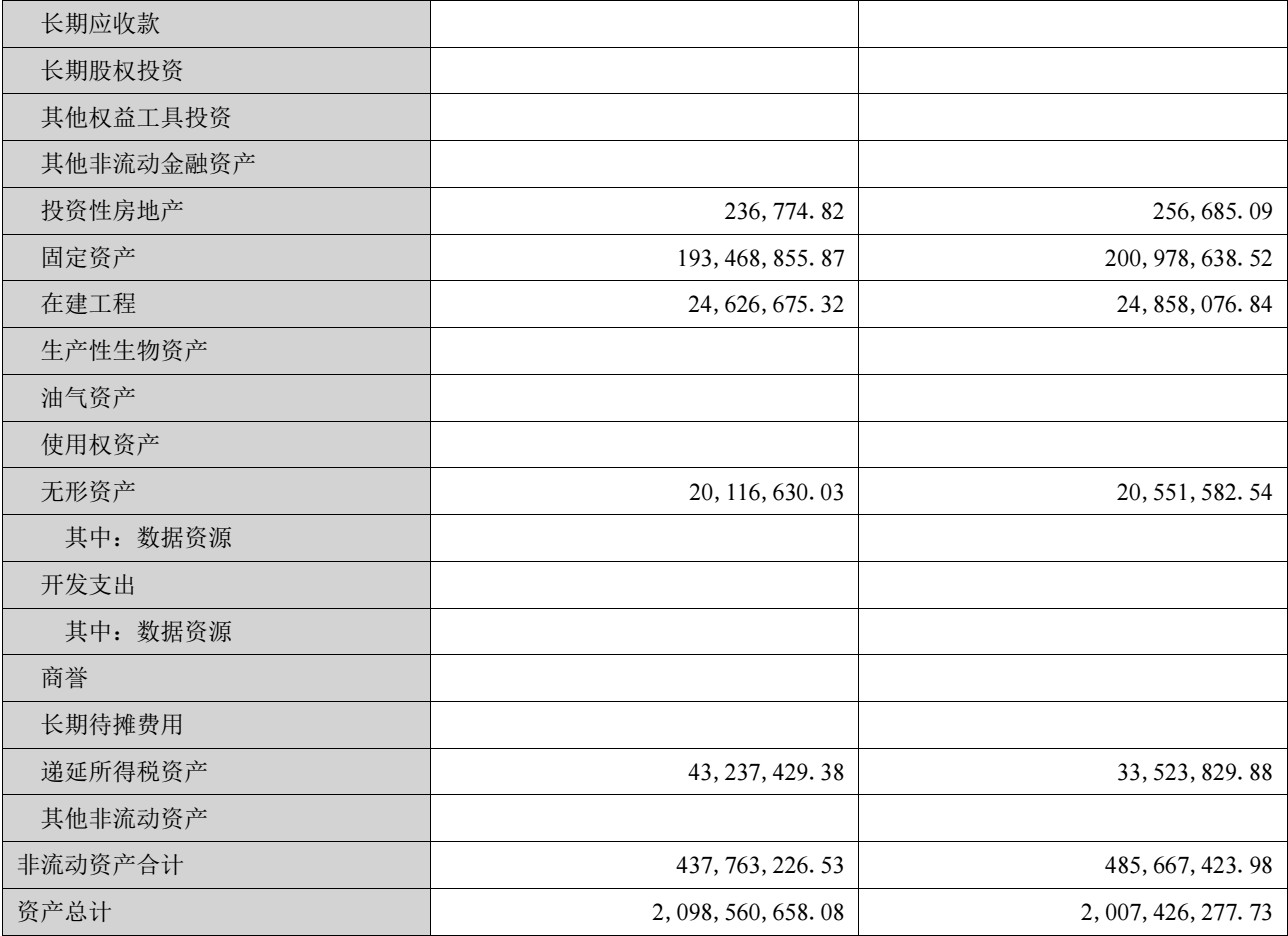
Regarding the asset-liability structure, at the end of Q1 2026, monetary funds were 113 million yuan, a significant decrease from 285 million yuan at the end of the previous year, mainly due to an increase in time deposits maturing within one year and principal-guaranteed cash management business. Correspondingly, non-Current Assets due within one year increased from 157 million yuan at the beginning of the period to 292 million yuan. The ending balance of other payables was 98 million yuan, an increase from 69 million yuan at the beginning of the period, mainly due to increased sales expense investment.
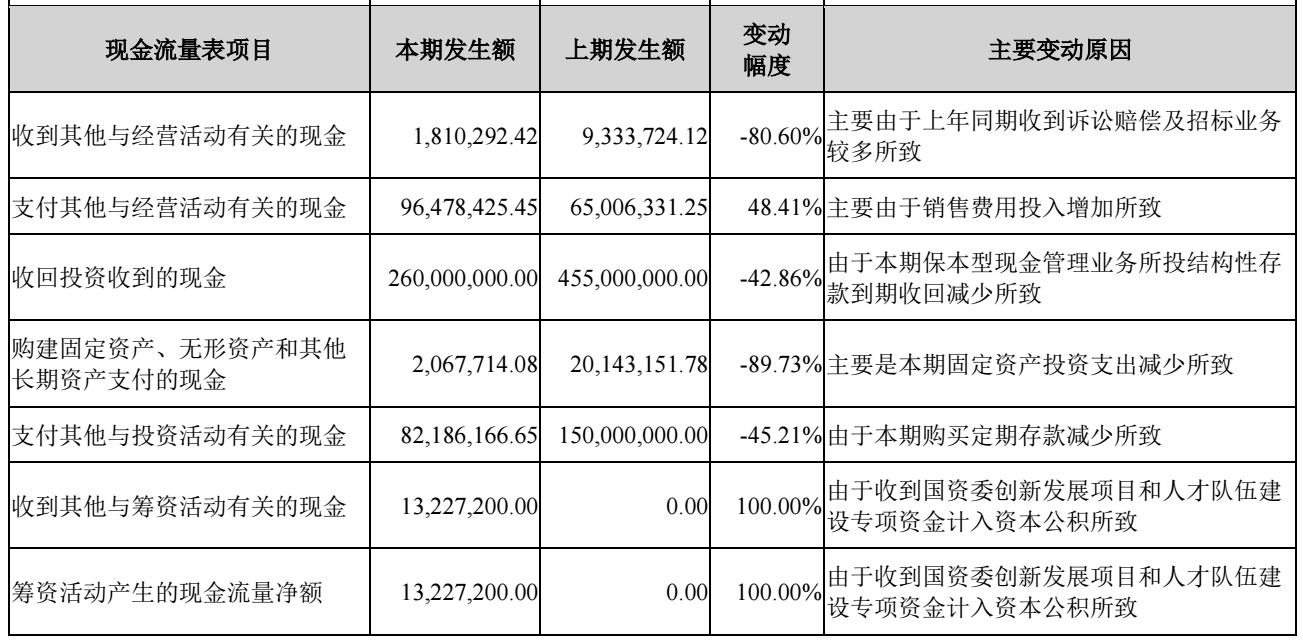
In terms of cash flow, net cash flow from operating activities in the first quarter was 54 million yuan, a year-on-year decrease of 17.07%, mainly affected by increased sales expense expenditures and the high base of non-recurring cash inflows such as litigation compensation received in the same period last year. In terms of financing activities, the company received 13 million yuan in special funds for the State-owned Assets Supervision and Administration Commission's innovation development projects and talent team construction.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|