DGN Responds to Regulatory Inquiry Letter: Plans to Acquire Four Ophthalmic Companies for 600 Million Yuan, Core Target's Value Appreciation Exceeds 12-FoldIssuing time:2026-04-02 18:25
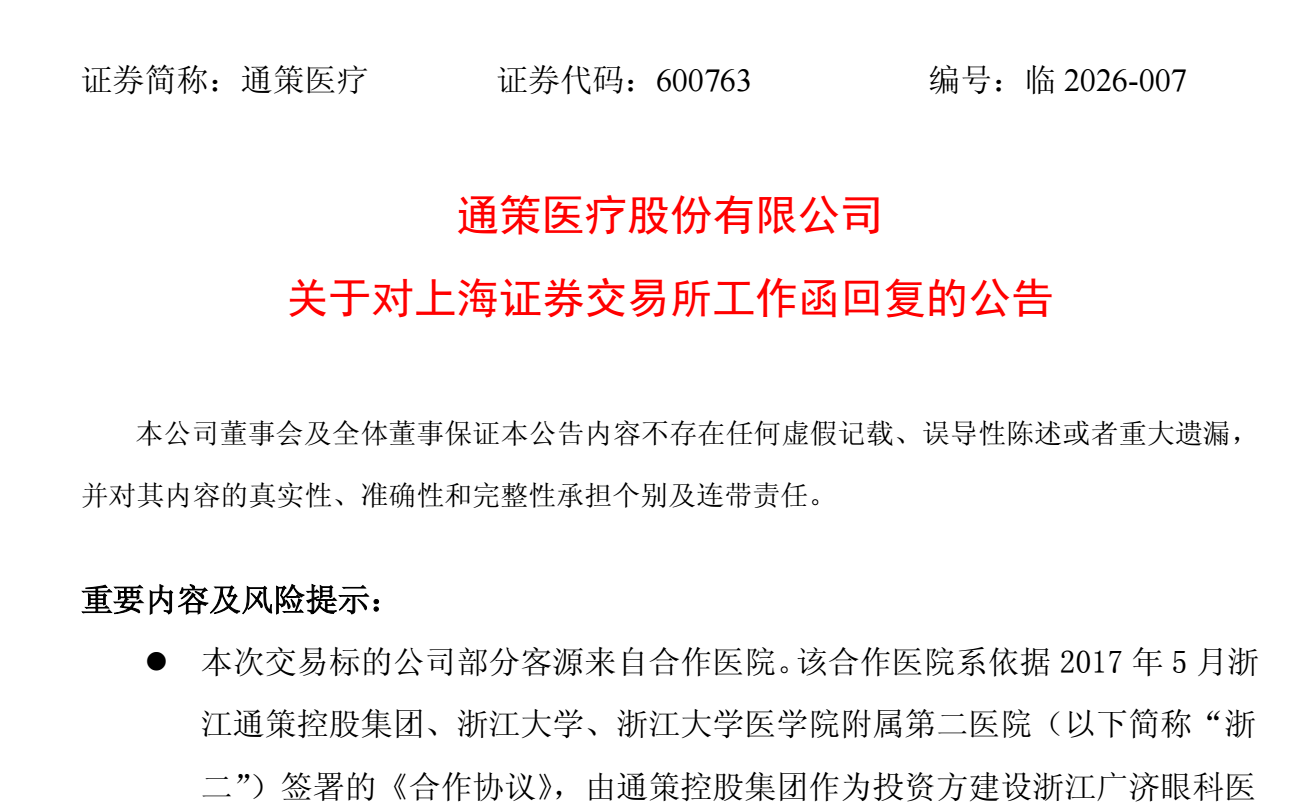
DentalGoodNews | On April 2, 2026, Tongce Medical (600763.SH) issued an announcement in reply to the regulatory working letter from the Shanghai Stock Exchange concerning the acquisition of assets from related parties. The announcement provided detailed supplementary disclosures on key issues such as the necessity of the transaction and the fairness of valuation and pricing, regarding the proposed acquisition of 100% equity in four ophthalmic and optometry companies, including Hangzhou Cunji Eyeglasses Co., Ltd. (hereinafter referred to as "Hangzhou Cunji Eyeglasses"), for 600 million yuan in cash. Addressing market concerns over the high premium, the announcement shows that the core target, Hangzhou Cunji Eyeglasses, had a net asset value of 50.8779 million yuan as of the valuation base date, December 31, 2025. The total equity value of shareholders assessed using the income approach was 703.2023 million yuan, representing an appraisal value-added rate as high as 1282.14%. Based on the transaction price of 600 million yuan, the overall premium rate remains at 1066.30%. According to previous reports by DGN, Tongce Medical announced on March 24, 2026, its intention to acquire four ophthalmic and optometry companies, including Hangzhou Cunji Eyeglasses, using its own funds of 600 million yuan. The aim is to establish optometry zones within its existing dental hospital network to build a "Bright Eyes and White Teeth" health ecosystem. This reply to the regulatory letter further clarifies the performance commitments. The counterparties to the transaction, including Tongce Eye Investment, have committed that the cumulative net profit of Hangzhou Cunji Eyeglasses from 2026 to 2028 will be no less than 180 million yuan, and the cumulative net profit from 2026 to 2030 will be no less than 300 million yuan. Regarding financial data, Hangzhou Cunji Eyeglasses has shown stable performance over the past two years. In 2024 and 2025, it achieved operating revenues of 158 million yuan and 153 million yuan, respectively; the Net Profit Attributable to Shareholders of the Parent Company was 54.0984 million yuan and 55.5848 million yuan, respectively. Based on the 2025 data, this acquisition corresponds to a static price-to-earnings (P/E) ratio of 12.65 times. The appraisal institution, Zhejiang Zhonglian Assets Appraisal Co., Ltd., believes that Hangzhou Cunji Eyeglasses operates under a light-asset model, where the P/E ratio better reflects its actual value compared to the price-to-book (P/B) ratio. Furthermore, the value-added rate falls within the comparable transaction range for the industry, indicating the pricing is fair. Additionally, the reasonableness of the valuation assumptions was a key focus of this disclosure. The announcement mentions that Hangzhou Cunji Eyeglasses currently uses its operating premises located in the West Lake International Trade Building free of charge. Through a supplementary agreement, the related party has stipulated that Hangzhou Cunji can use the site free of charge on a long-term basis until the property can no longer be used. Meanwhile, part of the customer base of the assessed entity comes from Zhejiang Guangji Eye Hospital. The cooperation agreement between the two parties has been extended to May 2037, with the assumption that it can be renewed upon expiration. In terms of business structure, the core products of Hangzhou Cunji Eyeglasses—orthokeratology lenses (OK lenses) and myopia control lenses—generated revenue of 88.9876 million yuan in 2025, accounting for 58.27% of its main business revenue. Future revenue forecasts indicate that revenue is expected to grow from 165 million yuan in 2026 to 185 million yuan in 2030, representing a compound annual growth rate (CAGR) of approximately 2.85%, which is lower than the industry's projected CAGR of 13.7%, suggesting the valuation forecast is achievable. Tongce Medical stated that this acquisition is a significant move in implementing its "Dental + Ophthalmology" dual-drive strategy. Leveraging the brand premium and existing customer traffic of its dental hospitals to establish optometry centers can effectively reduce customer acquisition costs and improve sales per square meter.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|