Swiss Dental Company COLTENE: Full-Year 2025 Net Sales Approximately 2.1 Billion RMB, Weakening Demand in the Chinese MarketIssuing time:2026-03-10 18:33
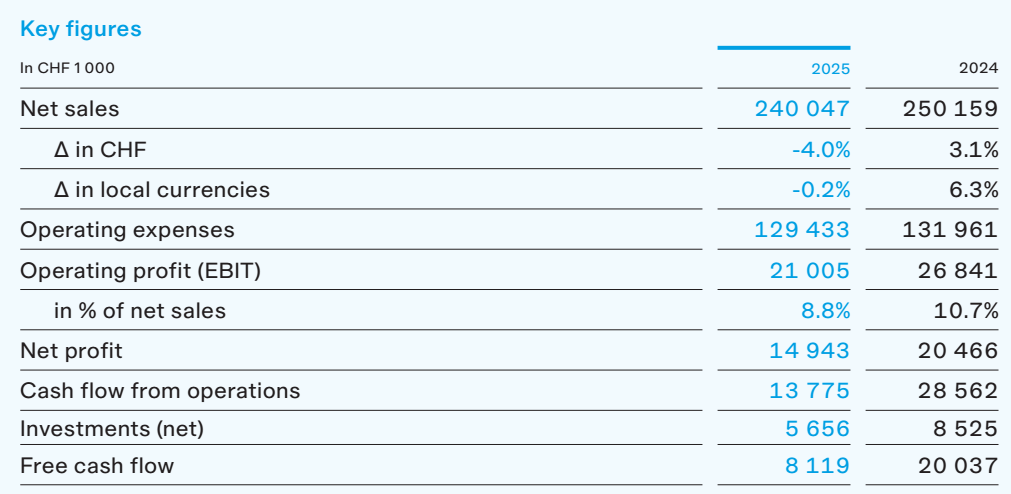
COLTENE 2025 Full-Year Net Sales RMB 2.138 Billion / EBIT Margin Drops to 8.8% / H2 Local Currency Growth at 4.7% DentalGoodNews | Swiss dental medical device manufacturer COLTENE Holding AG recently released its 2025 Annual Report. The report shows the company achieved full-year net sales of CHF 240 million (approximately RMB 2.138 billion), a year-on-year decrease of 4.0%. On a constant currency basis, sales were essentially flat compared to the previous year (-0.2%). In terms of profitability, the company's Operating Profit (EBIT) for 2025 was CHF 21.01 million (approximately RMB 187 million), a year-on-year decrease of 21.7%; net profit was CHF 14.94 million (approximately RMB 133 million), a year-on-year decrease of 27.0%. During the reporting period, the company's operating expenses were CHF 129 million (approximately RMB 1.149 billion), a year-on-year decrease of 1.9%. Despite some success in cost control, affected by the decline in revenue scale, the company's EBIT margin dropped from 10.7% in the previous year to 8.8%. The company stated that its 2025 performance was impacted by exchange rate fluctuations, US tariff policies, and adjustments to the distribution system. However, with the launch of new products and adjustments to market strategies, sales performance improved significantly in the second half of the year.
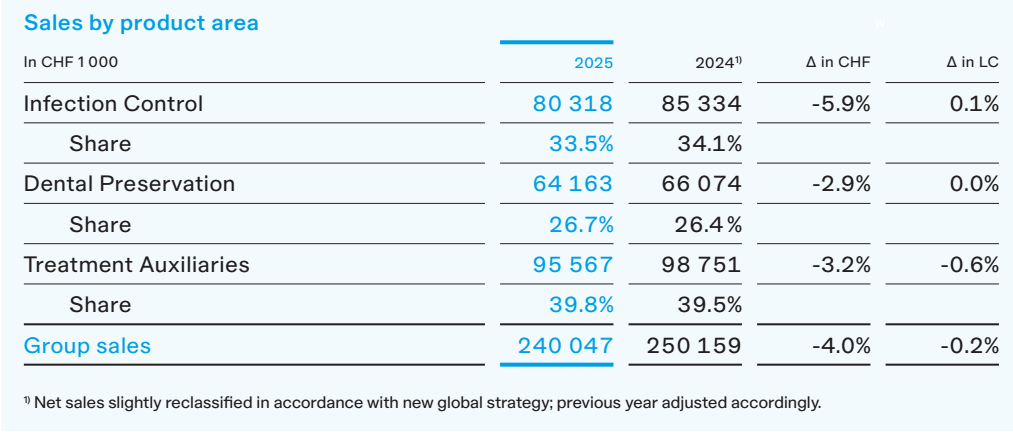
By business segment, Treatment Auxiliaries achieved sales of CHF 95.57 million (approximately RMB 851 million), a year-on-year decrease of 3.2%, accounting for 39.8% of total sales; Infection Control achieved sales of CHF 80.32 million (approximately RMB 716 million), a year-on-year decrease of 5.9%, accounting for 33.5% of total sales, with new instrument washers contributing incremental growth; Dental Preservation achieved sales of CHF 64.16 million (approximately RMB 572 million), a year-on-year decrease of 2.9%, accounting for 26.7% of total sales, with the root canal file series providing positive sales momentum.
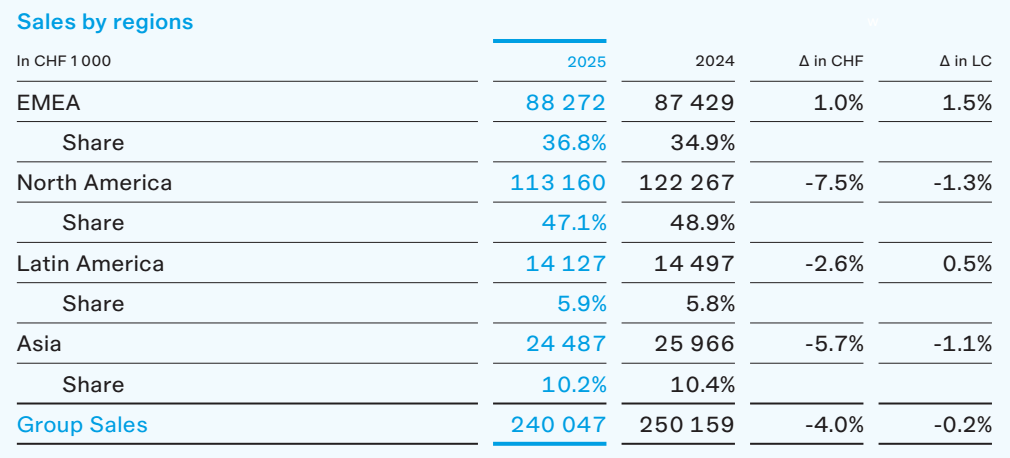
By region, North America remained the company's largest market. However, due to tariff uncertainties coupled with weak demand for high-priced infection control equipment, sales ultimately reached CHF 113 million (approximately RMB 1.007 billion), a year-on-year decrease of 7.5%, accounting for 47.1% of total sales; Europe, Middle East & Africa (EMEA) sales were CHF 88.27 million (approximately RMB 786 million), a year-on-year increase of 1.0%, accounting for 36.8% of total sales, with growth achieved in France, Benelux, Switzerland (home market), and the UK. Asia region sales were CHF 24.49 million (approximately RMB 218 million), a year-on-year decrease of 5.7%, accounting for 10.2% of total sales. The sales decline in the Asian market was mainly affected by weakening demand in China. Latin America region sales were CHF 14.13 million (approximately RMB 126 million), a year-on-year decrease of 2.6%, accounting for 5.9% of total sales.
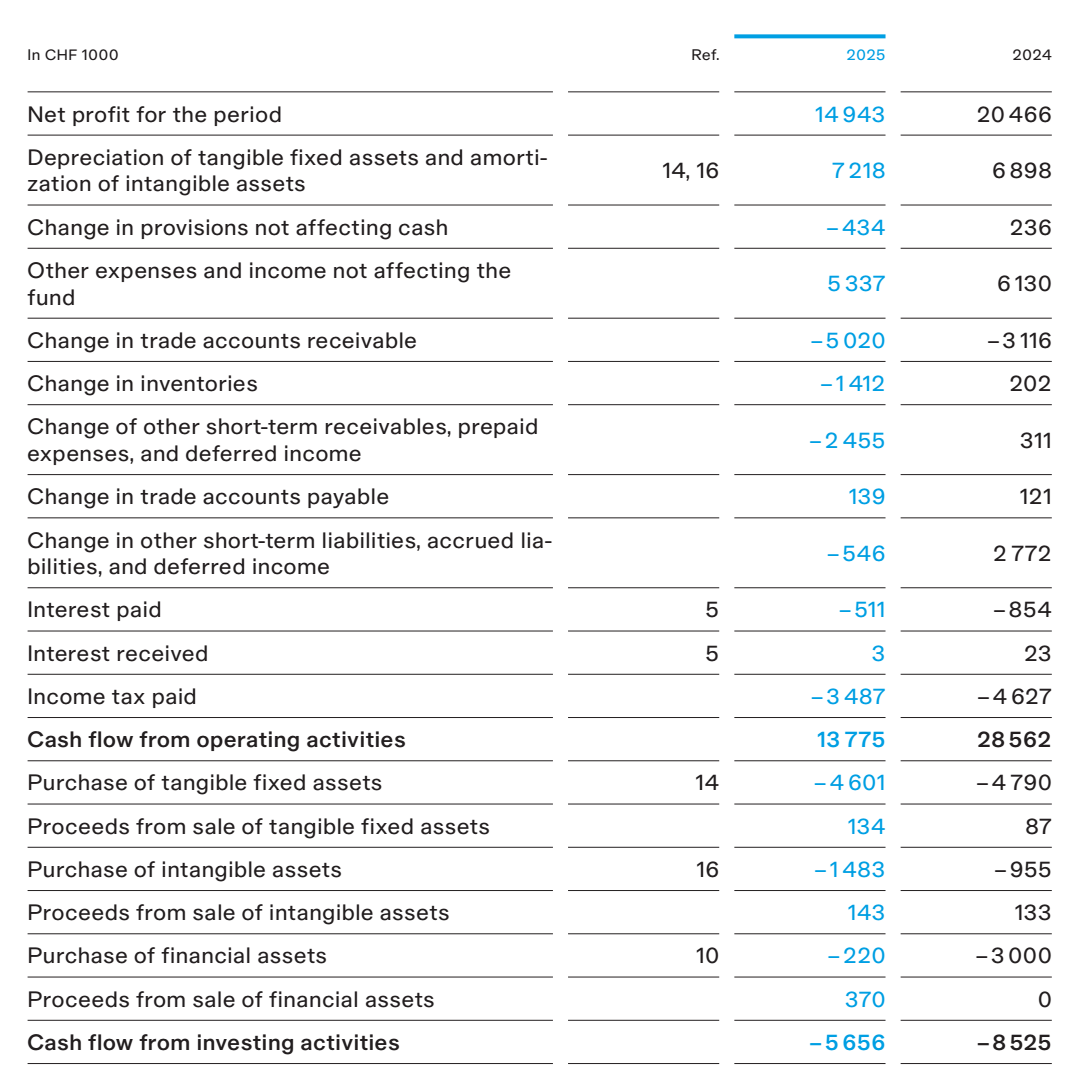
In terms of cash flow, the company's operating cash flow was CHF 13.78 million (approximately RMB 123 million), a significant decrease from CHF 28.56 million (approximately RMB 254 million) in 2024; free cash flow was CHF 8.12 million (approximately RMB 72.33 million), a significant decline from CHF 20.04 million (approximately RMB 179 million) in the previous year. The company stated this was mainly due to decreased profitability and increased working capital.
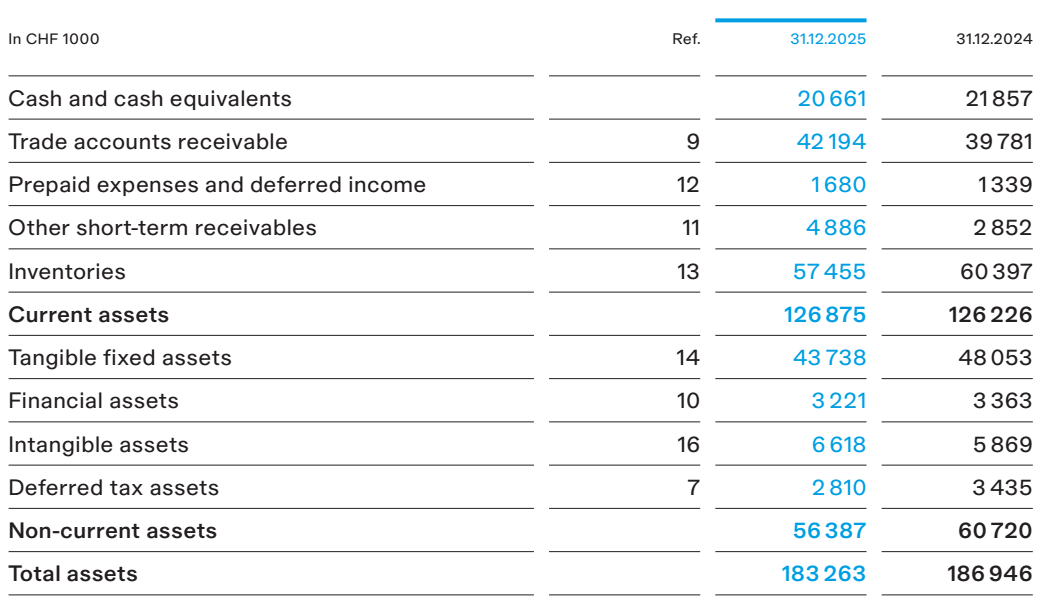
Regarding assets and liabilities, as of December 31, 2025, the company's total assets were CHF 183 million (approximately RMB 1.630 billion), a slight decrease from CHF 187 million (approximately RMB 1.666 billion) in 2024; Shareholders' Equity was CHF 101 million (approximately RMB 900 million), with an equity ratio of 54.9%. Net debt was CHF 26 million (approximately RMB 232 million). COLTENE pointed out in the report that the 2025 performance volatility was mainly influenced by factors including exchange rate fluctuations, uncertainty in US tariff policies, and order delays resulting from the optimization of the distributor system. Additionally, the global macroeconomic environment and geopolitical tensions in some regions also suppressed investment demand for dental equipment. In terms of strategic advancement, the company continues to advance its 2025–2027 strategic plan, building comprehensive treatment solutions around its three core business segments of Dental Preservation, Treatment Auxiliaries, and Infection Control. It has launched new products including instrument washers and root canal file systems to strengthen its product portfolio "from endodontics to restoration." For the 2026 outlook, management expects a moderate improvement in sales and profit margins as the distribution system adjustments are completed and new product contributions increase. The medium-to-long-term target of 3%–5% organic growth is maintained, with plans to increase the EBIT margin to 13%–15%.
【GOODNEWS】 Content for industry reference only (based on public info & professional judgment); not for decision-making. Readers bear full responsibility for their own judgment and risks.
Copyright © This Platform. Unauthorized reproduction & commercial use prohibited.
Errata, contributions & cooperation: Contact customer service via WeChat:HDSW_001
|
✉️
Subscribe to Our
Newsletter
We curate important stories and exclusive insights, delivered straight to your inbox.
In-depth analysis · Exclusive content · Fast-moving news
|